Gratitude Portfolio: Building Wealth with Purpose

Gratitude Portfolio is an approach to wealth creation that looks beyond investment returns. Financial success is often measured by how much we invest, how much our portfolio grows, and whether we achieve our financial goals. However, meaningful wealth can also provide the freedom to pursue personal ambitions, support loved ones, and contribute to causes that matter. A well-planned investment journey can therefore serve more than one purpose. It can help you work towards financial independence while giving you the flexibility to make a positive difference in the future. At Beesawa Securities, we believe investment decisions should reflect your financial goals, risk profile, and long-term aspirations. What Is a Gratitude Portfolio? A Gratitude Portfolio is not a specific mutual fund, scheme, or investment product. Instead, it represents a mindset towards wealth creation and financial planning. The concept is simple: Build Wealth → Achieve Financial Freedom → Use Financial Freedom Meaningfully When investors understand the purpose behind their investments, maintaining financial discipline during changing market conditions can become easier. For instance, financial goals may include: Consequently, connecting investments with meaningful objectives can make the overall financial journey more structured. How Investing Can Support a Purposeful Wealth Mindset 1. Start With Clear Financial Goals Before selecting a mutual fund or another investment option, first understand why you are investing. Rather than simply saying, “I want good returns,” define a specific financial objective. A clear target can make it easier to determine the investment amount, time horizon, and suitable level of risk. For example: Therefore, clearly defined goals can help you evaluate investment options more thoughtfully. 2. Make SIP a Habit A Systematic Investment Plan (SIP) allows investors to invest a fixed amount at regular intervals. As a result, it can encourage consistency and financial discipline. Instead of attempting to predict the best time to enter the market, investors can continue investing systematically over a longer period. Moreover, regular investments combined with the potential benefits of compounding may support long-term wealth creation. Beesawa Securities also provides SIP-oriented investment solutions for investors who want to build wealth gradually. 3. Diversify Your Investments Concentrating all your money in a single investment can increase concentration risk. On the other hand, diversification can help spread exposure across different securities and asset classes. Depending on the scheme and investment strategy, investors may consider exposure to: However, diversification does not mean simply owning a large number of funds. Instead, your portfolio should reflect your financial objectives, investment horizon, and risk profile. Think Long Term, Not Short Term Financial markets can experience significant movements over short periods. Consequently, reacting emotionally to every market change can make it harder to follow a long-term investment strategy. A long-term approach allows investors to focus on their financial objectives rather than short-term market noise. More importantly, it encourages investors to review their strategy based on changes in their circumstances instead of reacting to every price movement. A useful question to ask is: “Has my financial goal changed, or has only the market changed?” If your goals and investment strategy remain appropriate, short-term volatility may not necessarily require an immediate change to your investment plan. The Role of Gratitude in Financial Planning Financial planning is not only about numbers. It is also about understanding what your money enables you to achieve. A gratitude-based approach can encourage investors to appreciate the progress they have already made while continuing to work towards future objectives. For example, instead of constantly asking: “How much more do I need?” you can also ask: “How can the wealth I am building improve my life and the lives of others?” This change in perspective can make the investment journey more meaningful. At the same time, it can encourage a balanced approach to financial goals, personal priorities, and future responsibilities. Wealth Creation and Giving Back As your financial position becomes stronger, you may decide to allocate a portion of your wealth towards causes that are important to you. For example, this could involve: However, giving should be planned alongside your financial responsibilities. The objective is not to compromise essential financial goals. Instead, meaningful giving can become part of a broader wealth management strategy when your financial position allows it. How Mutual Funds Can Fit Into Your Financial Journey Mutual funds can support different financial objectives depending on the scheme selected, investment horizon, and investor’s risk profile. Some commonly used investment approaches include: Investment Approach Common Purpose SIP Regular and disciplined investing Lump Sum Investing surplus capital when appropriate STP Gradually transferring money from one investment to another SWP Making systematic withdrawals from investments Each approach has a different purpose. Therefore, the appropriate method depends on your financial situation, investment objective, time horizon, and risk tolerance. Build Wealth. Protect Goals. Create Impact. A successful financial journey does not necessarily end with wealth accumulation. Instead, financial freedom can provide the ability to use money thoughtfully to fulfil personal ambitions, support family members, and contribute to meaningful causes. Your financial journey can therefore be viewed through three simple stages: Invest → Grow → Give First, focus on disciplined investing. Next, give your wealth the opportunity to grow over time. Finally, when your financial goals are on track, consider how your resources can create a positive impact. This approach can help connect financial planning with a broader sense of purpose. Start Your Wealth Journey With Purpose Every investor has a different financial journey. For this reason, investment decisions should be based on individual goals, financial circumstances, and risk preferences. At Beesawa Securities, we aim to help investors understand their available options and make informed investment decisions. Whether you are starting your first SIP, investing a lump sum, planning systematic withdrawals, or looking to diversify your portfolio, a clear financial plan can make the process more structured. Ultimately, wealth is not only about how much you accumulate. It is also about what that wealth enables you to achieve. Start investing with purpose. Build wealth with discipline. Create a legacy with gratitude. Beesawa Securities Invest in Your Future. Build
Fund of Funds (FoF): Meaning, Types, Benefits, Risks & How It Works

Fund of Funds is a mutual fund structure that invests primarily in other mutual fund schemes rather than directly investing in individual stocks, bonds or other securities. It can provide investors with exposure to multiple investment strategies, asset classes, sectors or geographical markets through a single investment. For investors who find it difficult to select and monitor several schemes independently, this structure can offer a more convenient approach to portfolio diversification. Depending on the scheme, the underlying funds may be managed by the same fund house or by different fund managers. However, convenience does not eliminate investment risk. The performance, costs and risk profile of the product depend significantly on the underlying schemes. This article explains the meaning of a Fund of Funds, how it works, its major types, potential benefits and important risks investors should consider. What Is a Fund of Funds? A Fund of Funds (FoF) is a mutual fund scheme that invests in one or more other mutual fund schemes. Instead of directly purchasing individual securities, the FoF allocates money to selected underlying funds. These funds may invest in equities, bonds, commodities, international markets or other permitted investment strategies, depending on the FoF’s objective. A simple structure looks like this: Investor → Fund of Funds → Underlying Mutual Funds → Securities For example, an FoF may invest in several equity-oriented schemes to provide diversified equity exposure. Another may allocate across debt, equity and commodity-oriented funds according to its stated strategy. The exact investment approach depends on the scheme’s objectives and mandate. How Does a Fund of Funds Work? The process can be understood in three basic stages. Step 1: Investor Invests in the FoF The investor purchases units of the Fund of Funds in accordance with the scheme’s applicable terms. Step 2: FoF Allocates the Money The fund manager invests the collected capital in selected underlying mutual fund schemes. The allocation depends on the investment objective. It may focus on a particular asset class, sector, investment style, geography or combination of these. Step 3: Underlying Funds Invest in Securities The underlying mutual funds then invest in their respective securities, such as stocks, bonds or other permitted instruments. Therefore, the investor gets indirect exposure to the underlying assets through the FoF. Active vs Passive Fund of Funds FoFs can also differ based on how the underlying allocation is managed. Actively Managed FoF An actively managed FoF involves the fund manager selecting and monitoring underlying schemes. The manager may consider factors such as: The manager may also rebalance the portfolio when the scheme’s strategy requires it. Passively Managed FoF A passive structure generally follows a predefined benchmark, allocation model or investment strategy. Instead of frequently selecting and changing funds based on the manager’s views, the portfolio attempts to maintain the specified structure. The appropriate approach depends on the scheme’s objective and the investor’s preferences. Major Types of Fund of Funds FoFs can be classified according to their underlying investments and investment objectives. 1. Equity-Oriented FoF Equity-oriented FoFs primarily invest in equity mutual fund schemes. Depending on the mandate, the underlying portfolio may include different equity strategies or market-cap segments. Common examples include: These products may offer higher long-term growth potential but can also experience significant market volatility. 2. Debt-Oriented FoF Debt-oriented FoFs invest primarily in debt mutual fund schemes. The underlying funds may invest in different types of fixed-income securities, depending on their respective mandates. Factors affecting returns can include: Investors should understand the risk profile of the underlying debt funds rather than assuming that all debt-oriented products have low risk. 3. Hybrid FoF Hybrid FoFs combine exposure to multiple asset classes through underlying funds. Depending on the scheme, this may include equity and debt exposure in different proportions. Some common structures can include: The objective is generally to create a diversified portfolio rather than relying on a single asset class. 4. Commodity-Based FoF Commodity-oriented FoFs can provide exposure to commodity-related investment strategies through underlying funds. Depending on the structure and applicable regulations, exposure may include commodities such as: Such products can provide an alternative source of diversification, although commodity prices can be highly volatile. 5. Overseas FoF Overseas FoFs provide exposure to international markets through underlying funds. They may focus on: These products can make international diversification more accessible to investors. However, international investments also introduce additional factors such as currency movements, geopolitical developments and foreign-market conditions. 6. Domestic and Overseas FoF Some schemes may combine domestic and international investments. Depending on the mandate, the portfolio could provide exposure to: This approach can provide geographical diversification through a single investment structure. Benefits of Investing in a Fund of Funds A Fund of Funds can offer several potential advantages. 1. Diversification Diversification is one of the primary reasons investors consider this structure. A single FoF can provide exposure to multiple underlying schemes, which may cover different asset classes, investment styles, sectors or geographical markets. However, diversification depends on the actual portfolio. An FoF with limited underlying holdings may not provide as much diversification as a multi-fund structure. 2. Convenience Managing several mutual fund schemes independently can require regular research and monitoring. An FoF can simplify this process because the investor makes one investment while the fund manager handles the underlying allocation according to the scheme’s mandate. 3. Professional Fund Selection In an actively managed structure, professional fund managers are responsible for evaluating and selecting underlying schemes. This can reduce the need for investors to independently research every underlying fund. However, investors should still review the FoF’s strategy, portfolio and historical performance before investing. 4. Access to Specialized Strategies Some investment opportunities can be difficult to access or manage directly. An FoF may provide exposure to: This can help investors build broader exposure through a single product. 5. Lower Monitoring Effort An FoF can reduce the amount of portfolio monitoring required from an investor because the fund manager manages the allocation among underlying schemes. This can be particularly useful for investors who prefer a simplified investment structure. 6. Portfolio

CAGR vs XIRR: Which Return Measure Is Better for Mutual Fund Investors?

CAGR vs XIRR is an important concept for mutual fund investors who want to understand how effectively their money has performed. Although both measures express returns as an annualized percentage, they are designed for different investment situations. CAGR is generally useful when there is a single initial investment and a final value. XIRR, on the other hand, is more appropriate when an investment involves multiple cash flows made on different dates, such as SIP installments, additional investments, or withdrawals. Understanding which measure to use can help investors evaluate their portfolio performance more accurately. What Is CAGR? CAGR stands for Compound Annual Growth Rate. It represents the annualized rate at which an investment would have grown if it had increased at a steady compounded rate throughout the investment period. This measure is most suitable when there is: Example of CAGR Suppose you invest ₹6,00,000 as a lump sum and the investment grows to approximately ₹10.57 lakh after five years. If the investment achieved a 12% annualized growth rate, the return can be expressed as a 12% CAGR. In this situation, CAGR provides a straightforward way to understand the investment’s annualized growth. Lump-sum investment → CAGR What Is XIRR? XIRR stands for Extended Internal Rate of Return. Unlike CAGR, XIRR takes the timing of individual cash flows into account. This makes it particularly useful for investments involving multiple transactions on different dates. For example, an investor may: Since every transaction occurs on a different date, each amount remains invested for a different length of time. XIRR considers both the amount and date of each cash flow to calculate an annualized return. Multiple cash flows → XIRR Why XIRR Is Useful for SIP Investments SIP investments are made periodically rather than all at once. For example, consider an investor contributing ₹10,000 every month for five years. The first ₹10,000 installment may remain invested for almost five years, while the final installment may have been invested for only one month. Therefore, treating the entire investment as though it entered the market on the same day would not accurately represent the investor’s actual return experience. XIRR accounts for these different investment dates, making it a more suitable return measure for SIP portfolios. How Withdrawals and Additional Investments Change the Calculation Mutual fund portfolios can involve more than regular SIP installments. An investor might redeem ₹1 lakh after two years and then invest another ₹1 lakh one year later. For example, the cash flows could include: In such a situation, the investment has several cash flows occurring at different points in time. XIRR considers: It then calculates the annualized return based on the timing and value of these cash flows. CAGR vs XIRR: The Key Difference The easiest way to understand the difference is to look at the investment structure. Investment Situation Suitable Return Measure One-time lump sum investment CAGR One initial investment and final value CAGR Monthly SIP XIRR Multiple investments XIRR Investments plus withdrawals XIRR Irregular cash flows XIRR The key difference is the number and timing of cash flows. CAGR assumes a relatively simple investment journey, while XIRR provides a more detailed calculation when money enters or leaves the investment at different times. A Simple Example Imagine two investors who both have mutual fund portfolios worth ₹5 lakh today. Investor A Investor A invested ₹3 lakh as a lump sum five years ago and did not make any additional investments or withdrawals. For this investor, CAGR can provide a useful annualized return figure. Investor B Investor B invested ₹5,000 every month through an SIP over the same period. The total amount invested and the investment dates are different from Investor A’s. For Investor B, XIRR is generally more appropriate because each SIP installment has had a different investment period. This is why investors should not compare return figures without first understanding how the underlying investments were made. Why Choosing the Right Return Measure Matters A return percentage can look impressive, but its meaning depends on the investment structure behind it. For example, an investor who made one lump-sum investment and another investor who invested gradually through SIPs cannot always evaluate their performance using the same method. The timing of investments can significantly influence the actual annualized return. Using an appropriate calculation provides a clearer picture of how efficiently the invested money has performed. Common Mistakes Investors Should Avoid Using CAGR for SIP Investments Applying CAGR directly to a portfolio with frequent investments can provide a less meaningful picture of the investor’s actual experience. Ignoring Investment Dates When calculating returns involving multiple transactions, the date of each cash flow matters. Comparing Different Investment Structures Comparing a lump-sum investment with an SIP solely based on return percentages can be misleading if the underlying cash flows are different. Focusing Only on Returns Returns are important, but investors should also consider risk, investment horizon, asset allocation, and financial goals. A Simple Rule to Remember The difference can be remembered with a simple framework: One-time investment → CAGR SIP or multiple investments → XIRR Investments plus withdrawals → XIRR This simple distinction can help investors choose a more appropriate way to evaluate mutual fund performance. CAGR and XIRR Are Both Useful Neither measure is universally better than the other. CAGR is useful for understanding the compounded annual growth of a relatively straightforward investment. XIRR is better suited to portfolios where money moves in and out at different times. Therefore, the right calculation depends on the investment structure rather than personal preference. Final Thoughts CAGR vs XIRR is not about choosing one return measure over the other. It is about understanding which calculation matches your investment pattern. For a one-time lump-sum investment with no intermediate cash flows, CAGR can provide a simple view of annualized growth. For SIPs, additional investments, withdrawals, or other irregular transactions, XIRR can provide a more meaningful annualized return because it considers the timing of each cash flow. Before evaluating your mutual fund performance, ask one simple question: “Was my money invested at one

Planning Financial Freedom for Your Mother: A Gift That Lasts Beyond Flowers

Planning Financial Freedom for Your Mother can be one of the most meaningful gifts you can give her. Flowers fade, sweets are enjoyed, and many traditional gifts are eventually forgotten. Financial security, however, can provide lasting confidence and greater independence. Supporting your mother financially is not only about meeting her present-day expenses. It can also mean helping her prepare for future needs, personal goals, emergencies, and a comfortable lifestyle. A thoughtfully structured investment plan can be one part of this journey. Why Financial Independence Matters for Mothers Financial independence can provide more than monetary support. It can give a person greater confidence when making everyday and long-term financial decisions. For mothers who may have depended on family members for financial matters, building an investment corpus can provide greater control over their future. A dedicated financial plan can help address goals such as: The objective is not simply to accumulate money. It is to create financial resources that can support her needs over time. SIPs Can Be One Part of the Investment Plan A Systematic Investment Plan allows an investor to invest a fixed amount regularly in a mutual fund scheme. For example, an investor could choose to invest ₹1,000, ₹5,000, or ₹10,000 per month, depending on their financial capacity and investment objectives. Regular investing can encourage financial discipline and provide an opportunity for investments to grow over a longer period. However, mutual fund returns are market-linked and are not guaranteed. The choice of scheme should therefore depend on the investor’s financial goals, investment horizon, and risk tolerance. Five Reasons to Consider Investing for Your Mother’s Future 1. Start With an Amount That Fits the Budget Financial planning does not necessarily require a large initial investment. Starting with an affordable amount can help establish a consistent investing habit without putting unnecessary pressure on the household budget. As financial circumstances change, the investment amount can be reviewed and adjusted. 2. Build a Dedicated Financial Corpus A separate investment portfolio can help create funds for future requirements. Depending on the investment horizon, this corpus could potentially support expenses related to healthcare, travel, lifestyle choices, or other personal goals. Having dedicated financial resources may also reduce dependence on family members for every unexpected expense. 3. Encourage Greater Financial Independence Financial independence is not only about having a large corpus. It is also about having the confidence and resources to make financial decisions independently. A well-structured portfolio can help your mother participate more actively in decisions concerning her own financial future. 4. Give Investments More Time to Grow Time can be an important factor in wealth creation. When investments remain invested for longer periods, compounding can potentially have a greater impact. However, the appropriate investment option depends on the remaining time before the financial goal and the level of market risk that the investor can comfortably accept. 5. Prepare for Future Expenses Financial needs can change over time. Healthcare expenses, lifestyle requirements, travel plans, and unexpected costs may increase in the future. Planning ahead can make it easier to manage these expenses without putting excessive pressure on other sources of income. Start With Her Goals, Not With a Mutual Fund One of the most common mistakes in investment planning is beginning with the question: “Which mutual fund has given the highest return?” A better approach is to first understand the investor’s requirements. Before selecting an investment, consider: Once these questions are answered, suitable investment options can be evaluated. Create a Goal-Based Investment Strategy Different financial goals require different approaches. Short-Term Goals Money required in the near future may not be suitable for investments carrying significant market volatility. For short-term requirements, liquidity and capital preservation may be more important considerations. Medium-Term Goals For goals several years away, investors can evaluate investment options based on their time horizon, financial position, and risk tolerance. Long-Term Goals For longer-term objectives, equity-oriented mutual funds may be considered by investors who understand and can tolerate market fluctuations. The important point is that the investment should match the goal rather than simply chasing the highest historical return. Financial Planning Is More Than Investing Investing is only one component of a comprehensive financial plan. Before committing money to market-linked investments, it is important to consider whether your mother has adequate emergency savings and appropriate financial protection. The overall plan may include: This broader approach can make the financial plan more resilient. Review the Investment Plan Regularly Financial circumstances do not remain the same forever. Income, expenses, health requirements, financial goals, and risk tolerance can change with time. Therefore, investments should be reviewed periodically to determine whether they remain aligned with current objectives. A review does not necessarily mean frequently buying and selling investments. Instead, it means checking whether the portfolio continues to serve its intended purpose. The Real Gift Is Financial Confidence A saree, flowers, chocolates, or a special meal can make your mother happy today. But helping her build a financially secure future can provide benefits that extend much further. An investment of ₹1,000, ₹5,000, ₹10,000, or another amount that fits the family’s budget may appear small initially. Over time, consistent investing, appropriate asset allocation, and patience can potentially help create a meaningful financial corpus. The goal should not be to promise extraordinary returns. It should be to build a sensible financial plan that reflects her needs, goals, and comfort with risk. Final Thoughts Planning Financial Freedom for Your Mother is ultimately about giving her greater financial confidence and control over her future. The most valuable investment is not necessarily the one with the highest past return. It is the one that is appropriately matched to the investor’s goals, time horizon, financial situation, and risk profile. Whether you are helping your mother begin investing or reviewing an existing portfolio, start with her needs rather than market trends. Because sometimes, the most meaningful way to say “Thank you, Mom” is not just through a gift today, but by helping create a financial plan that supports her tomorrow. Disclaimer: Mutual fund investments are

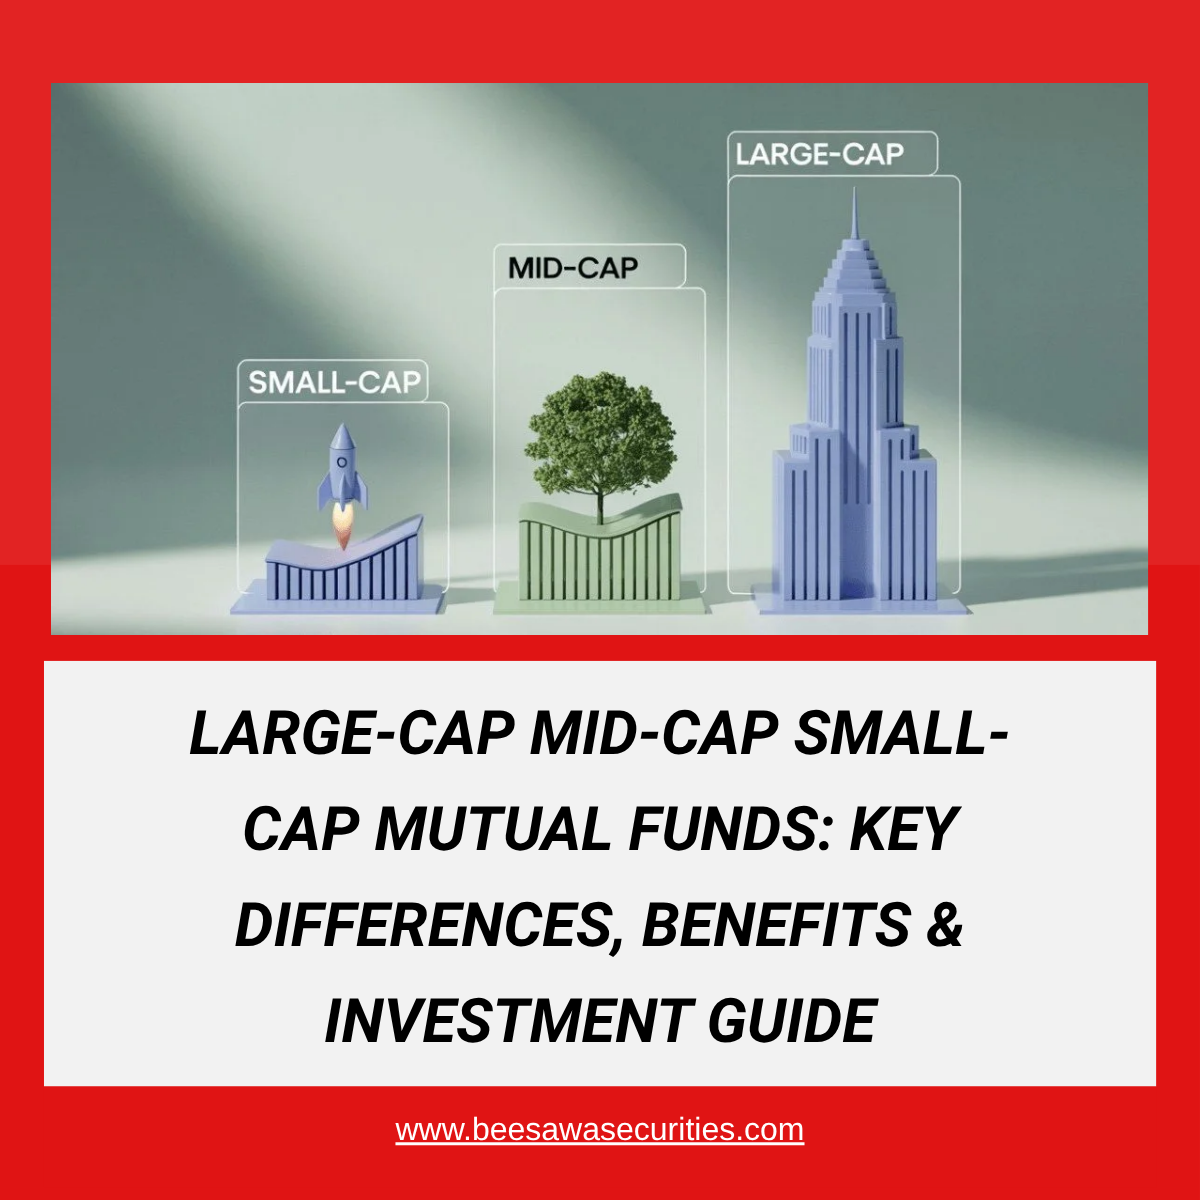
Large-Cap, Mid-Cap & Small-Cap Mutual Funds: Understanding the Key Differences Before You Invest

Large-Cap Mid-Cap Small-Cap Mutual Funds are among the most popular categories of equity mutual funds in India. If you are planning to invest in mutual funds, understanding these categories is essential before making any investment decision. While all three invest in equity shares, they differ in terms of company size, risk level, growth potential, and suitability for different investors. Therefore, choosing the right category depends on your financial goals, investment horizon, and ability to handle market fluctuations. What Are Large-Cap, Mid-Cap and Small-Cap Mutual Funds? Equity mutual funds primarily invest in shares of listed companies. Generally, these companies are classified according to their market capitalization (Market Cap), which represents the total market value of a company’s outstanding shares. According to SEBI: Accordingly, mutual funds are categorized based on the companies they invest in. For example, a Large-Cap Fund must invest at least 80% of its assets in large-cap companies. What Is a Large-Cap Mutual Fund? A Large-Cap Mutual Fund mainly invests in India’s largest and most established companies. As a result, these funds generally offer greater stability compared to other equity fund categories. Moreover, they usually invest in businesses with proven financial performance, established brands, and consistent earnings. Because of these qualities, many investors consider large-cap funds a suitable option for long-term wealth creation. Key Features Examples A typical portfolio may include: Since these companies have proven business models and strong financials, they are often considered relatively stable investments. Suitable For What Is a Mid-Cap Mutual Fund? Unlike large-cap funds, Mid-Cap Mutual Funds invest in medium-sized companies that are still expanding. Consequently, these businesses often offer higher growth potential. However, they also experience greater market fluctuations than large-cap companies. As these companies continue to expand, they may eventually become tomorrow’s market leaders. Key Features Example Consider a manufacturing company expanding into international markets. Although it has already built a strong domestic presence, it still has considerable room to grow. Mid-cap funds often invest in businesses at this stage. Suitable For What Is a Small-Cap Mutual Fund? Small-Cap Mutual Funds invest in smaller companies that are usually in the early stages of business growth. Although these businesses have the potential to generate impressive long-term returns, they also carry higher investment risk. Therefore, investors should be prepared for greater price volatility. At the same time, maintaining a long investment horizon can help manage short-term fluctuations more effectively. Key Features Example Imagine a young technology company developing an innovative product. If the business succeeds, investors may benefit from substantial growth over time. On the other hand, not every small company becomes successful, making careful diversification important. Suitable For A Simple Way to Understand the Difference Imagine three friends running different businesses. Friend A – Large-Cap One friend owns a supermarket chain operating across India. This business represents a Large-Cap Fund. Friend B – Mid-Cap Another friend manages a regional retail chain that is expanding into multiple cities. This business represents a Mid-Cap Fund. Friend C – Small-Cap Meanwhile, the third friend has launched an innovative startup. This business represents a Small-Cap Fund. Comparison of Mutual Fund Categories Feature Large-Cap Mid-Cap Small-Cap Company Size Largest companies Medium companies Smaller companies Risk Level Low Moderate High Growth Potential Moderate High Very High Volatility Low Moderate High Stability High Moderate Lower Investment Horizon 5+ Years 7+ Years 10+ Years Suitable For Conservative investors Balanced investors Aggressive investors Which Category Should You Choose? The right choice depends entirely on your financial goals and risk appetite. Choose Large-Cap Funds If Choose Mid-Cap Funds If Choose Small-Cap Funds If Is Investing in All Three Categories a Good Idea? For many investors, diversification can be an effective strategy. Instead of relying on a single category, spreading investments across different market capitalizations may help balance growth and stability. An illustrative allocation could be: Fund Category Allocation Large-Cap 50% Mid-Cap 30% Small-Cap 20% However, this is only an example. Your ideal allocation should always depend on your financial objectives, age, investment horizon, and risk profile. Why SIP Can Help Build Long-Term Wealth Regardless of the category you choose, investing through a Systematic Investment Plan (SIP) offers several advantages. Firstly, it encourages disciplined investing by allowing you to invest regularly. Secondly, SIPs help you benefit from rupee cost averaging during different market conditions. In addition, long-term investing allows the power of compounding to work in your favour. As a result, investors can gradually build wealth without worrying about short-term market movements. SIPs help you: Develop disciplined investing habits. Invest consistently. Benefit from rupee cost averaging. Reduce the impact of market volatility. Build wealth through compounding. Common Mistakes Investors Should Avoid Many investors make avoidable mistakes while selecting equity mutual funds. For example, some focus only on recent returns instead of long-term consistency. Similarly, others ignore their own risk tolerance and investment horizon. As a result, they often make emotional decisions that affect long-term wealth creation. Common mistakes include: Instead, focus on diversification, patience, and a long-term investment strategy. Final Thoughts Selecting the right equity mutual fund category is not about chasing the highest returns. Instead, it involves choosing investments that align with your financial goals, investment horizon, and risk appetite. While large-cap funds offer greater stability, mid-cap funds provide a balance between growth and risk. Meanwhile, small-cap funds have the potential to deliver higher long-term returns, although they come with greater volatility. Ultimately, a diversified portfolio combined with disciplined SIP investing can help you build sustainable wealth over time.

How to Choose the Right Mutual Funds for Your Financial Goals

How to Choose the Right Mutual Funds is one of the most important questions every investor should answer before starting their investment journey. While mutual funds have become one of the most popular investment options for wealth creation, selecting the right scheme requires more than simply choosing a fund with the highest past returns. Every investor has different financial goals, investment timelines, and risk tolerance. A mutual fund that works well for one person may not be suitable for another. The right investment decision should always be based on your financial objectives rather than market trends or recommendations from others. This guide explains the key factors you should consider before selecting a mutual fund and how to align your investments with your long-term financial goals. Why Choosing the Right Mutual Fund Matters Mutual funds offer professional fund management, diversification, and access to different asset classes. However, investing without understanding your financial requirements can lead to unsuitable investment choices. Selecting the right fund helps you: A well-planned investment strategy begins with selecting funds that match your personal financial needs. Step 1: Define Your Financial Goals Before selecting any mutual fund, identify the purpose of your investment. Some common financial goals include: Each financial goal has a different investment horizon, which influences the type of mutual fund you should consider. Step 2: Determine Your Investment Horizon Your investment period plays an important role in fund selection. Short-Term Goals (Up to 3 Years) For shorter investment horizons, investors generally prefer relatively stable investment options with lower volatility. Debt-oriented mutual funds or conservative hybrid funds may be suitable depending on individual financial circumstances. Medium-Term Goals (3–5 Years) Investors with medium-term objectives may consider balanced investment strategies that combine growth potential with relatively lower risk. Hybrid funds are often evaluated for such goals. Long-Term Goals (More Than 5 Years) Long-term investors usually have more time to manage market fluctuations. Equity-oriented mutual funds have historically offered better wealth creation potential over longer investment periods, although they carry higher market risk. Step 3: Understand Your Risk Tolerance Every investor has a different comfort level with market fluctuations. Ask yourself: Based on your answers, your risk profile may be: Conservative Investor Prefers stability over high returns. Generally considers lower-risk investment options. Moderate Investor Looks for balanced growth while managing risk. May prefer diversified portfolios with both equity and debt exposure. Aggressive Investor Seeks long-term capital appreciation and is comfortable with market volatility. May consider equity-focused investment strategies. Understanding your risk tolerance helps narrow down suitable mutual fund categories. Step 4: Know the Different Types of Mutual Funds Understanding various mutual fund categories helps investors make informed decisions. Equity Mutual Funds These funds primarily invest in company shares. Suitable for long-term wealth creation but subject to market fluctuations. Examples include: Debt Mutual Funds These schemes invest mainly in fixed-income securities such as government bonds and corporate debt. They generally experience lower volatility compared to equity funds. Hybrid Mutual Funds Hybrid funds combine equity and debt investments. They aim to balance growth potential with risk management. Index Funds Index funds aim to replicate the performance of a market index such as the Nifty 50 or Sensex. They typically have lower expense ratios because they follow passive investment strategies. Sectoral and Thematic Funds These funds focus on specific industries or investment themes. While they may offer higher growth potential, they also carry higher concentration risk. Step 5: Evaluate the Fund’s Historical Performance Past performance should never be the only selection criterion, but it provides useful insights. Instead of focusing only on one-year returns, evaluate performance over: Also compare performance against: Consistency is often more valuable than occasional outperformance. Step 6: Check the Expense Ratio The expense ratio represents the annual fee charged for managing the mutual fund. A lower expense ratio allows a greater portion of your investment to remain invested, potentially improving long-term returns. While expenses are important, they should be evaluated alongside the overall quality of the fund. Step 7: Review the Fund Manager’s Track Record The experience and investment philosophy of the fund manager can significantly influence long-term performance. Consider factors such as: Experienced fund managers often demonstrate disciplined decision-making during volatile market conditions. Step 8: Analyze the Portfolio Composition Before investing, review the fund’s portfolio. Look for: A diversified portfolio generally provides better risk management than one concentrated in a few companies or sectors. Step 9: Compare Risk-Adjusted Performance Higher returns do not always indicate a better mutual fund. Evaluate whether returns have been generated while managing risk effectively. Consider factors such as: This provides a more balanced view of fund performance. Step 10: Align Investments with Your Financial Plan A mutual fund should complement your overall financial strategy. Before investing, ask yourself: If the answer is yes, the fund may be suitable for your financial plan. Common Mistakes Investors Should Avoid Many investors make avoidable mistakes while selecting mutual funds. Some of the most common include: Avoiding these mistakes can improve long-term investment outcomes. Why Diversification Is Important Diversification helps reduce portfolio risk by spreading investments across different asset classes and sectors. A diversified mutual fund portfolio may include: This approach helps reduce the impact of poor performance in any single investment category. Should You Invest Based on Market Trends? Many investors invest in mutual funds because a particular category is currently performing well. This approach can be risky. Instead of chasing market trends, focus on: Successful investing is built on consistency rather than reacting to short-term market movements. Final Thoughts How to Choose the Right Mutual Funds is not about finding the fund with the highest recent returns—it is about selecting investments that align with your financial goals, investment horizon, and risk tolerance. A well-chosen mutual fund can help you build long-term wealth, achieve important financial milestones, and create a disciplined investment journey. Rather than relying on market trends or popular recommendations, take time to evaluate the fund’s objectives, historical performance, expense ratio, portfolio quality, and management team. Remember, the best mutual fund is

What Is NAV in Mutual Funds? A Beginner’s Guide to Understanding Net Asset Value

What Is NAV in Mutual Funds is one of the most common questions asked by new investors. Many people believe that a mutual fund with a lower Net Asset Value (NAV) is cheaper or offers better returns. However, this is one of the biggest misconceptions about mutual fund investing. In reality, NAV simply represents the price of one unit of a mutual fund. It does not indicate whether a fund is expensive, cheap, or likely to generate higher returns. To make informed investment decisions, it is important to understand what NAV means, how it is calculated, and why it should not be the primary factor when selecting a mutual fund. What Is NAV? NAV, or Net Asset Value, is the per-unit value of a mutual fund. It represents the market value of all the securities held by the mutual fund after deducting its liabilities and expenses, divided by the total number of outstanding units. In simple terms, NAV is the price you pay when purchasing one unit of a mutual fund and the price you receive when redeeming your units. Since the value of the fund’s investments changes every business day, the NAV is also updated daily. How Is NAV Calculated? The calculation of NAV is straightforward. NAV = (Total Value of Assets – Total Liabilities) ÷ Total Number of Outstanding Units Where: This daily calculation ensures that every investor buys or redeems units at the latest available value. Understanding NAV with an Example Suppose you invest ₹10,000 in two different mutual funds. Fund A Fund B At first glance, Fund A may appear more attractive because its NAV is lower. However, the number of units alone does not determine your returns. Now assume that after one year, both funds generate a 10% return. Fund A Fund B Although the number of units is different, the total return remains exactly the same. This example clearly shows that a lower NAV does not make a mutual fund a better investment. Common Myth: Lower NAV Means Better Returns One of the biggest misconceptions among investors is that mutual funds with lower NAV offer greater growth potential. This belief is incorrect. Unlike stocks, where a lower share price may sometimes indicate undervaluation, NAV simply reflects the value of the fund’s existing assets divided among investors. Whether a fund has an NAV of ₹20 or ₹200, future returns depend on the performance of the underlying portfolio—not on the NAV itself. Therefore, investors should avoid choosing mutual funds based solely on their NAV. Why Does NAV Matter? Although NAV should not determine your investment decision, it still plays an important role. Determines Purchase Price When you invest in a mutual fund, NAV determines the number of units you receive. Determines Redemption Value When you sell your mutual fund units, the redemption amount is calculated using the prevailing NAV. Helps Track Investment Value Changes in NAV reflect the daily movement in your investment’s value. Indicates Portfolio Performance While NAV itself does not measure quality, its movement over time reflects the overall performance of the fund’s underlying investments. What Factors Should You Consider Instead of NAV? Instead of focusing on NAV, investors should evaluate the overall quality of the mutual fund. Some important factors include: 1. Long-Term Performance Review the fund’s performance over multiple market cycles rather than short-term returns. Consistency is often more important than temporary outperformance. 2. Investment Objective Ensure that the fund aligns with your financial goals. For example: Different mutual funds serve different purposes. 3. Risk Profile Every mutual fund carries a different level of risk. Investors should select schemes that match their risk tolerance and investment horizon. 4. Fund Manager’s Track Record The experience and investment approach of the fund manager can significantly influence long-term performance. Evaluate the consistency of the fund manager across different market conditions. 5. Expense Ratio The expense ratio represents the annual cost of managing the mutual fund. Lower expenses can improve long-term returns, especially for long-duration investments. 6. Portfolio Quality Review the sectors, companies, and asset allocation within the fund. A well-diversified portfolio generally provides better risk management. Does a Higher NAV Mean a Fund Is Expensive? Another common misunderstanding is that mutual funds with a high NAV are expensive. This is also incorrect. A higher NAV usually indicates that the fund has appreciated over time because of its investment performance. It does not mean that the fund has become overvalued or offers lower future returns. Similarly, a lower NAV does not automatically indicate greater growth potential. The focus should always remain on the fund’s ability to generate consistent returns while managing risk effectively. When Should Investors Pay Attention to NAV? NAV becomes relevant in specific situations, such as: However, it should not be used to compare two different mutual funds as the primary basis for investment decisions. Each fund has a different launch date, investment strategy, and portfolio composition, making direct NAV comparisons misleading. Common Mistakes Investors Should Avoid Many investors make avoidable errors while evaluating mutual funds. Some of the most common mistakes include: Avoiding these mistakes can lead to better investment decisions over the long run. Final Thoughts What Is NAV in Mutual Funds is an important concept that every investor should understand before investing. NAV is simply the per-unit price of a mutual fund and helps determine the value of your investment. However, it is not an indicator of whether a fund is good, cheap, or capable of delivering higher returns. Rather than selecting a mutual fund based on its NAV, investors should focus on factors such as long-term performance, portfolio quality, risk profile, fund management, expense ratio, and alignment with their financial goals. Remember, the best mutual fund is not the one with the lowest NAV—it is the one that consistently helps you achieve your investment objectives while managing risk effectively over the long term. Disclaimer: Mutual fund investments are subject to market risks. Read all scheme-related documents carefully before investing.

Ways to Invest in Mutual Funds: A Complete Guide for Beginners

Ways to Invest in Mutual Funds have become more convenient than ever before. Whether you are a first-time investor or someone looking to diversify your portfolio, there are multiple options available to start your mutual fund journey. From investing directly through an Asset Management Company (AMC) to using online investment platforms, each method offers unique features and benefits. Choosing the right investment route is just as important as selecting the right mutual fund. Therefore, understanding the available options can help you invest with greater confidence and convenience. Why Mutual Funds Have Become Popular Mutual funds have gained significant popularity in India over the past few years. Increasing financial awareness, higher disposable incomes, and the need for portfolio diversification have encouraged more investors to consider this investment option. Unlike investing directly in individual stocks, mutual funds allow investors to pool their money into professionally managed portfolios consisting of equities, debt instruments, or a combination of both. Additionally, they offer flexibility in investment amount, investment horizon, and risk level, making them suitable for a wide range of financial goals. How Can You Invest in Mutual Funds? Before choosing an investment platform, investors should understand the two primary investment methods. Lump Sum Investment A lump sum investment involves investing a large amount of money in a mutual fund scheme at one time. This option is generally suitable for investors who have surplus funds available and wish to invest immediately. Systematic Investment Plan (SIP) A Systematic Investment Plan (SIP) allows investors to invest a fixed amount at regular intervals, such as monthly or quarterly. This approach encourages disciplined investing and helps spread investments across different market conditions. Most investment platforms support both lump sum investments and SIPs, allowing investors to choose the method that best suits their financial objectives. 1. Invest Directly Through an Asset Management Company (AMC) One of the simplest and most cost-effective methods is investing directly with the Asset Management Company. AMCs manage mutual fund schemes by collecting money from investors and investing it in different financial assets such as equities, bonds, and money market instruments. Investors can purchase mutual fund units directly through: Benefits of Investing Directly Investing directly with an AMC allows investors to choose Direct Plans. Direct Plans generally have: Since there are no intermediaries involved, the overall cost of investing is lower compared to regular plans. However, this option is generally more suitable for investors who are comfortable selecting mutual funds independently. 2. Invest Through Online Investment Platforms Digital investment platforms have transformed the mutual fund investment experience. Today, investors can access hundreds of mutual fund schemes from different AMCs through a single online platform. After completing registration and Know Your Customer (KYC) formalities, investors can compare funds, start SIPs, make lump sum investments, and monitor their portfolios conveniently. Advantages of Online Platforms Online investment platforms offer several benefits, including: These platforms are particularly useful for investors who prefer managing all their investments in one place. 3. Invest Through a Mutual Fund Distributor Investors who require professional assistance may choose to invest through a mutual fund distributor. Distributors recommend suitable schemes based on an investor’s financial goals, investment horizon, and risk tolerance. They also assist with documentation and investment processes. Benefits of Using a Distributor A distributor can help: However, investments made through distributors are generally Regular Plans. Regular Plans include distributor commissions, resulting in a higher expense ratio compared to Direct Plans. Therefore, investors should carefully evaluate whether the additional guidance justifies the higher cost. 4. Invest Through Registrar and Transfer Agents (RTAs) Registrar and Transfer Agents (RTAs) provide another convenient route for investing in mutual funds. In India, major RTAs include CAMS and KFin Technologies (formerly Karvy Fintech). These organizations provide services for multiple Asset Management Companies through a single platform. Investors can invest online through their portals or visit their service centers to complete the investment process. Services Offered by RTAs RTAs provide several useful services, such as: This option is particularly beneficial for investors holding mutual funds from multiple fund houses. Comparing Different Ways to Invest Investment Method Suitable For Key Advantage Important Consideration Direct Through AMC Experienced investors Lower expense ratio Requires self-research Online Investment Platform Most investors Convenience and multiple fund options Compare platform features Mutual Fund Distributor Beginners Professional guidance Higher expense ratio due to commissions Registrar and Transfer Agent (RTA) Investors using multiple AMCs Single platform for several fund houses Limited advisory services Each investment method serves different investor needs. Therefore, the right choice depends on your knowledge, investment preferences, and financial goals. Factors to Consider Before Choosing an Investment Method Before selecting an investment route, investors should evaluate several important factors. Investment Cost Lower expense ratios can improve long-term returns. Therefore, compare the costs associated with each investment method before making a decision. Ease of Use Choose a platform that offers a simple investment process, portfolio tracking, and convenient transaction management. Research and Support If you are a beginner, professional guidance may be valuable. On the other hand, experienced investors may prefer managing their own investments through Direct Plans. Convenience Online access, mobile applications, and paperless transactions can significantly improve the overall investment experience. Which Investment Method Is Best? There is no single method that suits every investor. If you are confident about selecting mutual funds independently, investing directly through an AMC can reduce costs over the long term. If you prefer convenience and access to multiple fund houses, online investment platforms can be an excellent choice. Similarly, beginners who require expert assistance may find value in working with a mutual fund distributor. Meanwhile, investors managing schemes across different AMCs may benefit from using Registrar and Transfer Agent platforms. Ultimately, the best option depends on your investment knowledge, financial objectives, and personal preferences. Final Thoughts Ways to Invest in Mutual Funds have evolved significantly, giving investors greater flexibility and convenience than ever before. Whether you choose to invest directly through an Asset Management Company, use an online investment platform, seek guidance from a distributor, or access services

Why Mutual Funds Are Becoming the No.1 Investment Choice in 2025

Across India, the way people think about money is changing.Instead of relying only on fixed deposits, recurring deposits, or traditional savings, investors are now turning toward Mutual Funds — and for good reason. In 2025, people want investments that support Wealth Creation, offer transparency, and fit their lifestyle. Mutual funds are the perfect match, which is why they are becoming the No.1 preferred investment choice.Let’s explore the real reasons behind this powerful trend. Best Mutual Funds Make Investing Simple & Stress-Free One of the biggest advantages of mutual funds is that they make investing extremely easy.The Best Mutual Funds come with professional fund managers who take care of research, stock selection, and risk management.Mutual funds are preferred because they offer:1. Simple investment structure2. Easy entry for beginners3. No need for daily market tracking4. Multiple options for every financial goalThis simplicity and clarity have made mutual funds the go-to investment option for everyone — whether new or experienced. SIP Investment Is Transforming How India Saves & Grows Money SIP Investment (Systematic Investment Plan) has become one of the biggest financial movements in India.With SIP, anyone can invest small amounts monthly and steadily build wealth over time. SIP Investment helps with:1. Building discipline2. Compounding wealth automatically3. Reducing market risk with rupee-cost averaging4. Creating long-term Wealth Creation SIP is not just an investment; it’s a modern savings habit.This is a major reason mutual funds are trending strongly in 2025. High Return Mutual Funds Are in High Demand Today’s investors want growth, not just safety.This is why High Return Funds, especially equity mutual funds, are gaining popularity.People are increasingly attracted to these funds because they: Investors in 2025 are more informed and prefer options that help achieve financial freedom faster — making High Return Funds a major trend. Goal-Based Investing Through Mutual Funds Is Rising People are no longer investing without direction.They are investing with purpose, and mutual funds offer dedicated solutions for every life goal.Some of the most common goals include: How to Start SIP: Easy, Digital, and 100% Convenient One of the biggest reasons mutual funds are trending is their digital convenience.Anyone can learn How to Start SIP and begin investing online in just a few minutes. The entire process is paperless, fast, and investor-friendly — making SIP and mutual funds the most convenient investment system in India. Want to Start Investing in Mutual Funds? Contact Now A Perfect Fit for All Budgets & Risk Levels Mutual funds are extremely flexible. Whether someone wants low risk, moderate risk, or high growth — there is a fund category for everyone. Investors can choose: This flexibility ensures mutual funds support short-term stability and long-term Wealth Creation. Need Help With SIP Investment or Choosing the Best Mutual Funds? If you want expert guidance on: You can reach out anytime for consultation and support to Beesawa Securities

How to Become a Crorepati with Minimum Investment Using the 15x15x15 Rule

Becoming a crorepati in India no longer requires a huge inheritance or a high-paying job. With smart investing, discipline, and time on your side, you can build wealth steadily — even with a modest income. One of the most talked-about strategies in the world of mutual fund investing is the 15x15x15 rule, which has helped lakhs of Indian investors achieve long-term financial goals through Systematic Investment Plans (SIPs). Let’s understand how this rule works, why it’s so effective, and how you can start using it today. What is the 15x15x15 Rule in SIP Investing? The 15x15x15 rule is a simple formula: invest ₹15,000 every month for 15 years, and expect an average return of 15% per annum. This rule is rooted in the power of compound interest — where not just your principal, but also the returns earned are reinvested and grow over time. Here’s what it looks like in numbers: 15x15x15 SIP Table 15×15×15 Rule — SIP Projection Monthly SIP Duration Expected Return (p.a.) Final Corpus ₹15,000 15 years 15% ₹1.01 crore Illustration for educational purposes. Actual mutual fund returns vary; consider consulting a SEBI-registered advisor. Over 15 years, your total investment will be ₹27 lakhs. But due to compounding, the value grows to over ₹1 crore — a profit of nearly ₹74 lakhs. The real magic happens when you stay invested longer. If you continue for another 15 years without investing anything additional, the same amount can grow to ₹10 crores. Why SIP is the Best Method for Long-Term Mutual Fund Investment A Systematic Investment Plan (SIP) is a disciplined way to invest a fixed amount in mutual funds every month. It works like a recurring deposit — but in equity or hybrid mutual funds, which have the potential to offer higher long-term returns.According to data from AMFI (Association of Mutual Funds in India), Indian mutual funds have over 5.84 crore SIP accounts, and monthly SIP inflows have crossed ₹13,000 crore in recent months. This surge in interest is because SIPs allow investors to invest without worrying about market volatility.When markets are down, you accumulate more mutual fund units. When markets rise, your units gain value. This is known as rupee cost averaging, and it’s one of the biggest advantages of SIPs. The Power of Compounding: Small Amounts, Big Results To illustrate compounding, Nippon India Mutual Fund explains that the returns earned in one period are reinvested and generate returns in the next — and this cycle keeps repeating. That’s how a ₹15,000 SIP for 15 years turns into over ₹1 crore. Extend this period by another 15 years, and the same ₹1 crore could grow to nearly ₹10 crore. Even smaller SIPs can yield impressive returns, as shown below: SIP Growth Table SIP Growth — 15 Years Projection Monthly SIP Total Investment (15 yrs) Final Corpus @15% Profit Earned ₹5,000 ₹9 lakh ₹33.4 lakh ₹24.4 lakh ₹10,000 ₹18 lakh ₹66.8 lakh ₹48.8 lakh ₹15,000 ₹27 lakh ₹1.01 crore ₹74 lakh Returns are illustrative. Mutual fund investments are subject to market risks. Please consult a SEBI-registered advisor before investing. You don’t need to start with ₹15,000. Start with what you can, and increase your SIP gradually every year. Best Mutual Fund Types to Apply the 15x15x15 Rule For long-term SIPs, equity mutual funds are the most suitable, as they offer higher return potential compared to debt or hybrid funds. Within equities, the following categories are ideal: Some of the best-performing funds (as of 2025) to consider include: Best Mutual Funds Table Best Mutual Funds (2025) Fund Name Fund Type Parag Parikh Flexi Cap Fund Flexi Cap Mirae Asset Large Cap Fund Large Cap Axis Growth Opportunities Fund Flexi/Mid Cap SBI Small Cap Fund Small Cap ICICI Prudential Bluechip Fund Large Cap Note: Always consult a SEBI-registered financial advisor before investing. Tips to Maximize SIP Returns While SIPs are convenient and long-term focused, you can make the most of them by following a few principles:Avoid Timing the Market: SIPs work best when done regularly, regardless of market cycles.Start Early: The earlier you start, the more you benefit from compounding.Be Consistent: Never skip SIPs — even when markets fall.Review Annually: Monitor fund performance and rebalance if needed.Top-up SIPs: Increase your monthly SIP amount by 10% each year as your income grows. The 15x15x15 Rule is Your Shortcut to ₹1 Crore The idea of becoming a crorepati in India is often seen as distant or difficult. But with the 15x15x15 formula — ₹15,000 per month for 15 years at 15% returns — it becomes a realistic, achievable goal. This method is ideal for salaried professionals, freelancers, and business owners who want to build long-term wealth without taking unnecessary risks.By using SIPs in mutual funds, investors not only benefit from compound interest but also gain from market volatility through rupee cost averaging. It’s time to stop waiting and start investing. 💡 Ready to begin?Use a SIP calculator to estimate your returns and choose the best SIP plan for your financial goals. Smart SIP Calculator Monthly SIP (₹) Expected Annual Return (%) Investment Duration (years) Contribution Timing End of month Start of month Calculate Reset Results update instantly — default assumes end-of-month SIP. Total Invested ₹0 Estimated Future Value ₹0 Profit ₹0 Monthly SIP — Annual Return (%) — Duration (years) — Total Months — Contribution timing — Note: This calculator assumes monthly compounding for the expected annual return and contributions at month start or end. Results are illustrative — actual mutual fund returns vary. Always consult a SEBI-registered financial advisor before investing.