How Is an IPO Listing Price Decided? Call Auction and GMP Explained

When a company launches an Initial Public Offering (IPO), one question attracts considerable investor attention: At what price will the stock list on the stock exchange? Suppose an IPO has an issue price of ₹1,119 per share. Will it list at ₹1,119, at a premium, or below its issue price? Investors often look at the company’s reputation, subscription figures and Grey Market Premium (GMP) to estimate the listing price. However, these factors do not directly determine the official opening price. The listing price is discovered through the stock exchange’s prescribed price-discovery mechanism, which evaluates buy and sell orders during a special pre-open call auction session. Understanding this process can help investors interpret listing-day movements and avoid relying entirely on unofficial market estimates. 1. What Happens on an IPO Listing Day? On listing day, an IPO stock goes through a special pre-open session before regular trading begins. During this session, investors submit eligible buy and sell orders, and the exchange evaluates them to discover an opening price. For example: The exchange evaluates the accumulated orders according to its applicable rules to determine the equilibrium opening price. Unlike continuous trading, the call auction collects orders during a specified period before matching eligible orders at the discovered price. Key takeaway: The company does not simply announce its listing price. It is determined through the stock exchange’s prescribed price-discovery process. 2. What Is a Call Auction in an IPO? A call auction is a mechanism used to discover an opening price by evaluating buy and sell orders collected during a specified period. Its objective is generally to determine a price that maximises the executable quantity, subject to the exchange’s applicable rules and tie-breaking criteria. The process broadly involves three stages: Stage 1: Order entry Investors submit buy and sell orders with specified prices and quantities during the permitted order-entry period. Stage 2: Price discovery The exchange evaluates the accumulated order book at different price levels to determine the equilibrium price under its prescribed methodology. Stage 3: Order matching and regular trading Eligible orders are matched at the discovered price. Unmatched orders are handled according to exchange rules, and continuous trading subsequently begins. This mechanism helps establish an opening price based on the available order book rather than relying solely on expectations or unofficial estimates. 3. Example: How Is the IPO Opening Price Calculated? Consider a hypothetical IPO with an issue price of ₹100 per share. During the call auction, investors place buy and sell orders at different prices. Suppose the exchange’s evaluation produces the following illustrative matched quantities: Candidate price Illustrative matched quantity ₹95 3,000 shares ₹105 6,000 shares ₹115 2,000 shares In this simplified example, ₹105 has the highest matched quantity. It could therefore be the equilibrium opening price, provided it also satisfies the applicable exchange rules and tie-breaking criteria. This example is illustrative, not an actual order book. In practice, the exchange evaluates cumulative buy and sell orders at different price levels. The highest buy order, lowest sell order or largest individual order does not automatically determine the listing price. The outcome depends on the interaction of the complete order book. 4. What Happens to Unmatched IPO Orders? Not every order is necessarily executed during the call auction. For example, a buy order priced below the discovered equilibrium price may remain unmatched. Similarly, a sell order priced above the equilibrium price may not be executed. Depending on the exchange’s rules and the conditions attached to the orders, eligible unmatched orders may be carried forward to regular trading. Once continuous trading begins, the stock price can change as fresh buy and sell orders enter the market. This is why the opening price and the price at which an investor eventually sells their shares may differ. 5. What Is GMP, and Does It Determine the Listing Price? GMP stands for Grey Market Premium. It refers to the unofficial premium at which IPO shares are indicated to trade in the grey market before their official listing. Suppose an IPO has an issue price of ₹1,119 per share and an indicative GMP of ₹200. Some market participants may estimate a potential listing price as follows: Estimated price = Issue price + Indicative GMP ₹1,119 + ₹200 = ₹1,319 per share. However, this is only an indicative estimate, not a guaranteed listing price. GMP reflects unofficial market activity and sentiment. It is not part of the stock exchange’s official price-discovery mechanism. The actual listing price may differ significantly because demand, supply, broader market conditions and investor expectations can change before listing. Important: Treat GMP as an informal market indicator, not a confirmed prediction of listing performance. 6. IPO Issue Price vs GMP vs Listing Price Understanding the difference between these three terms is important before investing in an IPO. Parameter Meaning IPO issue price The price at which shares are offered to investors in the IPO. GMP An unofficial indication of the premium or discount in the grey market. Listing price The official opening price determined through the stock exchange’s applicable price-discovery process. For example, if an IPO’s issue price is ₹1,119, its stock may list above or below that price depending on the order book and the price-discovery outcome. A high GMP does not guarantee a premium listing, and a low GMP does not necessarily mean the stock will list at a discount. 7. Can an IPO Stock Fall After Listing? Yes. A stock can decline even after listing at a premium to its issue price. Suppose an investor receives IPO shares at ₹1,119 and the stock opens at ₹1,300. The investor initially has an unrealised gain of ₹181 per share. If selling pressure increases and the price falls to ₹1,150, that unrealised gain decreases to ₹31 per share. If the stock subsequently falls below ₹1,119, its market value becomes lower than the IPO issue price. This example shows why a positive listing does not guarantee continued price appreciation. After listing, the stock price may be influenced by profit booking, valuation concerns, company fundamentals, market
Step-Up SIP vs Regular SIP: Benefits, Examples and Potential Returns

Step-Up SIP is an investment approach that allows investors to increase their monthly Systematic Investment Plan (SIP) contributions at predetermined intervals. As income grows, increasing investment contributions may help individuals work towards long-term financial goals. Starting a SIP is an important step towards building financial discipline. However, salaries, career opportunities and disposable income can change over time, while many investors continue investing the same monthly amount for years. This raises an important question: should your monthly investments remain constant even when your earning capacity increases? A Step-Up SIP offers a structured way to gradually increase contributions, potentially helping investors build a larger corpus over the long term. However, the right approach depends on income stability, financial commitments, risk tolerance and investment goals. 1. What Is a Step-Up SIP? A Step-Up Systematic Investment Plan is a method of investing in mutual funds where the SIP contribution increases at predetermined intervals, usually annually. Unlike a regular SIP, where the monthly contribution remains constant unless changed, a Step-Up SIP allows investors to increase their contributions by a fixed amount or percentage, depending on the facilities offered by the investment platform. For example, an investor may start with a monthly SIP of ₹1,00,000 and choose to increase it by 10% every year. Investment Year Monthly SIP Amount Year 1 ₹1,00,000 Year 2 ₹1,10,000 Year 3 ₹1,21,000 Year 4 ₹1,33,100 Year 5 ₹1,46,410 This gradual increase helps investors align their contributions with changing financial circumstances rather than committing to a substantially higher amount from the beginning. 2. Step-Up SIP vs Regular SIP: Understanding the Difference Both approaches encourage disciplined investing. The main difference is how contributions change over time. Feature Regular SIP Step-Up SIP Monthly contribution Remains constant unless changed Increases at predetermined intervals Investment approach Fixed contributions Gradually increasing contributions Flexibility Can be modified manually Increases may be scheduled automatically Income alignment Does not automatically reflect income growth Can be aligned with salary increments Total contribution Generally predictable Generally increases over time Suitable for Investors preferring consistent contributions Investors expecting growth in disposable income Neither approach is universally better. The appropriate choice depends on income stability, financial commitments, investment goals and the ability to increase contributions sustainably. 3. How Does a Step-Up SIP Work? A Step-Up SIP follows the same basic investment process as a regular SIP, with the additional feature of periodically increasing contributions. Consider an investor who starts with a monthly SIP of ₹1,00,000 and chooses an annual increase of 10%. This pattern continues according to the selected schedule. The key advantage is that investors can plan increases in advance instead of having to make a new investment decision every year. However, the planned increases should remain affordable and should not interfere with essential expenses, emergency savings or other financial commitments. 4. Step-Up SIP Returns: A Hypothetical Illustration One of the main differences between a regular SIP and a Step-Up SIP becomes visible over longer investment periods. Consider two hypothetical investors who begin with a monthly SIP of ₹1,00,000. Assuming a monthly investment return of 1%, equivalent to approximately 12.68% effective annual growth, the estimated investment values could be as follows. Investment Period Regular SIP Value Step-Up SIP Value 5 years ₹82.49 lakh ₹98.46 lakh 10 years ₹2.32 crore ₹3.37 crore 15 years ₹5.05 crore ₹8.68 crore 20 years ₹9.99 crore ₹19.89 crore Illustrative calculations assume investments are made at the beginning of each month, monthly compounding at 1%, and a 10% annual increase in the Step-Up SIP contribution. These figures are mathematical illustrations, not forecasts. Actual mutual fund returns fluctuate and are not guaranteed. The higher Step-Up SIP value reflects larger contributions as well as the potential effect of compounding. The illustration demonstrates how increasing contributions can potentially help investors accumulate a larger corpus over time. However, a Step-Up SIP does not automatically generate a higher rate of return. The difference primarily comes from investing more money over the investment period. 5. Why Consider a Step-Up SIP? A. Align Investments With Income Growth Income may increase through annual increments, promotions or career progression. A Step-Up SIP offers a structured way to direct a portion of additional income towards financial goals. For example, someone receiving an annual salary increment may choose to increase their SIP based on the additional amount they can comfortably invest. B. Help Manage Lifestyle Inflation As income increases, spending on shopping, entertainment, travel and lifestyle upgrades may also rise. Allocating a portion of additional income towards investments can help balance present lifestyle needs with future financial priorities. C. Support Long-Term Financial Goals Retirement planning, children’s education and purchasing a home may require substantial investments over time. Gradually increasing contributions may help investors work towards larger financial targets, particularly when the expected cost of a goal rises due to inflation. D. Encourage Progressive Financial Discipline Starting with an affordable investment amount may be more practical than committing to a large contribution immediately. A Step-Up SIP allows investors to begin at a comfortable level and increase contributions as their financial capacity improves. E. Provide a Structured Investment Approach A predetermined increase can reduce the need to reconsider contribution amounts frequently. Investors should still review their SIPs periodically to ensure that the contribution schedule remains suitable for their circumstances. 6. Is a Step-Up SIP Suitable for Everyone? Although Step-Up SIPs offer several potential advantages, they may not be appropriate for every investor. Individuals with stable income and predictable financial growth may find scheduled increases easier to manage. However, investors with irregular income, significant financial obligations or uncertain cash flows may prefer maintaining a fixed SIP and increasing it manually when circumstances permit. Before choosing a Step-Up SIP, consider: Increasing SIP contributions does not eliminate market risk. The objective should be to invest sustainably rather than increase contributions beyond one’s financial capacity. 7. How Much Should You Increase Your SIP Every Year? There is no universal percentage that works for every investor. Some individuals may consider an annual increase of 5%, while others may be comfortable with 10% or more. The

Jio IPO Effect on Reliance Industries: Wealth Creation or Valuation Risk?

Jio IPO effect on Reliance Industries is a key question for investors evaluating whether Jio Platforms’ public listing could unlock value for Reliance Industries (RIL) shareholders or introduce new valuation risks. The Jio Platforms IPO opened for subscription on October 21, 2026, with a price band of ₹1,065–₹1,119 per share and an issue size of approximately ₹30,213 crore at the upper end of the band. The issue is scheduled to close on October 23, with listing expected on October 28. Source: Moneycontrol. For Reliance Industries shareholders, however, the bigger question is not simply whether the IPO attracts strong demand. The real question is: Will Jio’s listing unlock additional value for Reliance shareholders, or has much of that value already been reflected in RIL’s valuation? The answer will depend on Jio’s post-listing valuation, earnings growth, debt reduction, monetisation opportunities and how the market values Reliance’s remaining businesses. 1. Why Does the Jio IPO Matter for Reliance Industries? Jio has evolved from a telecom business into a broader digital ecosystem covering: Reliance Industries owns approximately 66.4% of Jio Platforms, according to IPO-related reporting. This makes Jio one of the most important businesses within Reliance’s overall portfolio. The IPO gives public-market investors an opportunity to assess Jio through a separate listed valuation rather than estimating its worth entirely within Reliance Industries. This independent valuation benchmark could make it easier to analyse the contribution of Jio to RIL’s overall value. However, the final impact will depend on Jio’s market performance after listing and the valuation assigned to Reliance’s other businesses. 2. Could the Jio IPO Unlock Hidden Value in RIL? One of the biggest potential benefits for Reliance shareholders is value unlocking. Large conglomerates can trade at a holding-company discount because investors may find it difficult to assign separate valuations to all their businesses. Reliance Industries operates across several major areas, including: Before Jio’s listing, investors had to estimate the value of its digital business within RIL’s overall valuation. After listing, Jio will have an independently observable market price. This could help investors assess RIL using a sum-of-the-parts approach: Estimated RIL value = Jio + Retail + O2C + New Energy + Other Assets − Net Debt If Jio receives a strong market valuation and investors gain greater confidence in Reliance’s other businesses, the holding-company discount could potentially narrow. However, listing Jio does not guarantee that the market will assign a higher valuation to RIL. The parent company’s valuation will continue to depend on business performance, capital allocation, debt and market sentiment. 3. Jio’s Valuation Is the Key Variable The Jio IPO price band implies an equity valuation of approximately ₹10.3 lakh crore at the upper end, based on the reported share count and issue price. Reuters has reported a potential valuation of approximately $108.3 billion. Source: Reuters. This is a substantial valuation, making it important for investors to look beyond IPO demand and potential listing gains. The more important question is: Can Jio grow its earnings and cash flows sufficiently to justify its valuation over time? Jio already has enormous scale, but future growth may increasingly depend on: As the telecom market matures, subscriber growth alone may not be sufficient to sustain a premium valuation. Investors will also need to monitor pricing, customer retention, profitability and cash generation. A strong business can still deliver disappointing investment returns if its valuation already reflects very optimistic growth expectations. 4. Potential Positive Effects of the Jio IPO on Reliance Shareholders A. Independent Value Discovery The IPO provides a public-market valuation benchmark for Jio. This can help investors understand how much of Reliance’s overall value comes from its digital and telecom business. Over time, the market price and financial disclosures of Jio may provide additional information for analysing RIL’s sum-of-the-parts valuation. B. Potential Reduction in the Holding-Company Discount A separately listed Jio could make the overall Reliance structure easier to evaluate. If investors assign stronger valuations to Jio and gain confidence in Reliance’s other businesses, RIL could potentially benefit from a re-rating. However, this outcome is not automatic. Investors will still assess the parent’s corporate structure, debt, capital allocation and other business valuations. C. Improved Financial Flexibility The IPO is a fresh issue, with proceeds primarily intended to support Jio’s financial requirements, including repayment of borrowings at Reliance Jio Infocomm. Reports indicate that up to approximately ₹27,500 crore is earmarked for debt repayment. Source: Reuters. If the proceeds are used as planned, lower borrowings could improve financial flexibility and support future investment needs. However, investors should distinguish between debt reduction at Jio’s telecom subsidiary and debt reduction at Reliance Industries itself. The impact on the parent company’s financial position depends on the broader corporate structure and financial arrangements. D. Greater Independence in Future Fundraising Once listed, Jio could potentially access equity markets independently for future expansion. This may provide an additional source of funding for growth initiatives and reduce reliance on parent-level funding. The actual benefit will depend on Jio’s future capital requirements, market conditions and ability to generate cash internally. 5. Valuation Risks Investors Should Not Ignore The Jio IPO is not automatically positive for Reliance Industries shareholders. Several risks deserve attention. Risk 1: High Expectations A premium valuation creates high expectations. If Jio’s earnings, ARPU or cash flows do not grow as expected, the stock could face valuation compression. Even if the business continues growing, the share price may struggle if investors begin assigning it a lower valuation multiple. Risk 2: Telecom Competition Jio operates in a competitive telecom market. Competition from Bharti Airtel and other technologies could affect pricing power, customer retention and margin expansion. Investors should monitor whether Jio can increase revenue per user without weakening its competitive position. Risk 3: Growth Versus Valuation The market may already be pricing in substantial future growth from 5G, AI, cloud and digital services. If those opportunities take longer to generate meaningful revenue and profits, investors may revise their expectations. This means strong operating performance does not always translate into strong share-price appreciation when the

SIF vs AIF: Key Differences Between Specialised and Alternative Investment Funds

The Indian investment landscape is evolving, offering investors more opportunities beyond traditional investment products. While mutual funds remain a popular choice for wealth creation, specialised investment structures are also gaining attention. Two such options are Specialized Investment Funds (SIFs) and Alternative Investment Funds (AIFs). Both provide access to investment strategies that may go beyond conventional mutual fund approaches. However, they differ in their regulatory frameworks, minimum investment requirements, investment opportunities, liquidity and risk profiles. Understanding the differences between SIFs and AIFs can help investors evaluate which structure, if either, aligns with their financial goals, investment experience and risk tolerance. What Is a Specialized Investment Fund (SIF)? A Specialized Investment Fund (SIF) is an investment product introduced by the Securities and Exchange Board of India (SEBI) under the mutual fund regulatory framework. It aims to bridge the gap between conventional mutual funds and more sophisticated investment products. SIFs allow eligible investors to access specialised equity, debt and hybrid strategies, including certain permitted long-short strategies using derivatives, subject to regulatory limits. Key Features of SIFs The minimum investment threshold and regulatory framework are specified by SEBI. https://www.sebi.gov.in/legal/circulars/feb-2025/regulatory-framework-for-specialized-investment-funds-sif-_92299.html SIFs are designed for investors who understand market risks and want to explore strategies beyond conventional mutual funds. What Is an Alternative Investment Fund (AIF)? An Alternative Investment Fund (AIF) is a privately pooled investment vehicle that collects capital from investors and invests according to a defined investment policy. AIFs are regulated by SEBI under the SEBI (Alternative Investment Funds) Regulations, 2012. They can invest in a range of assets, including private equity, venture capital, private debt, listed securities and other permitted alternative investments. AIFs generally cater to sophisticated investors who have substantial investment capital, understand complex strategies and can tolerate potentially higher risks and limited liquidity. Categories of AIFs Category I AIFs These funds invest in sectors or activities considered socially or economically desirable. Examples include venture capital, startups and infrastructure-focused funds. Category II AIFs These include many private equity funds, private debt funds and other funds that do not fall under Category I or Category III. They generally cannot employ leverage except as permitted under applicable regulations. Category III AIFs These funds may use complex trading strategies, including derivatives and leverage, subject to regulatory conditions. Some follow hedge-fund-style strategies. Key Features of AIFs The regulatory framework and investment requirements are outlined in SEBI’s AIF regulations. https://www.sebi.gov.in/media/press-releases/may-2012/sebi-notifies-sebi-alternative-investment-funds-regulations-2012_22799.html SIF vs AIF: Key Differences Although both structures offer investment opportunities beyond conventional mutual funds, their characteristics and objectives differ. Parameter Specialized Investment Fund (SIF) Alternative Investment Fund (AIF) Regulatory framework SEBI mutual fund regulations and SIF provisions SEBI AIF Regulations, 2012 Minimum investment Generally ₹10 lakh Generally ₹1 crore Target investors Experienced investors seeking specialised strategies Sophisticated investors with substantial capital Investment structure Investment strategies within the mutual fund framework Privately pooled investment vehicle Investment opportunities Specialised equity, debt and hybrid strategies Private equity, venture capital, private debt and other permitted strategies Investment flexibility Advanced strategies within SIF-specific limits Depends on the AIF category and investment mandate Liquidity Depends on the strategy’s subscription and redemption terms Often restricted, particularly in closed-ended schemes Risk profile May involve derivatives, short exposure and concentrated risks May involve illiquidity, valuation uncertainty, leverage and private-market risks Disclosures Mutual fund disclosures with SIF-specific requirements Disclosures under AIF regulations and fund documents Investor suitability Investors who understand specialised market-linked strategies Investors able to assess complex strategies and potentially long commitments Note: This is a general comparison. Actual investment features, restrictions, liquidity and risks depend on the specific SIF strategy or AIF scheme. 1. Minimum Investment Requirements One of the most significant differences between SIFs and AIFs is the initial investment threshold. SIFs generally require a minimum investment of ₹10 lakh across the relevant fund’s SIF strategies at the PAN level. Certain regulatory exceptions apply, including for accredited investors. AIFs generally require a minimum investment of ₹1 crore per investor. Specific exceptions apply under the regulations, including for certain employees or directors of the fund or its manager and accredited investors. The lower entry threshold for SIFs may make them accessible to a broader group of investors. However, a lower minimum investment does not automatically make a product suitable for every investor. Investors should evaluate their financial position, investment experience and ability to absorb losses before committing capital. 2. Investment Strategies and Flexibility SIFs and AIFs differ in the investment strategies they can employ. SIFs may use specialised equity, debt, hybrid and permitted long-short strategies. Their investment activities remain subject to the mutual fund regulatory framework and the limits applicable to SIFs. AIFs can offer a wider range of investment approaches depending on their category and mandate. Certain funds may invest in unlisted companies, private businesses, venture capital opportunities, private credit or complex trading strategies. The key difference: SIFs offer specialised strategies within the mutual fund framework, while AIFs can provide exposure to a broader range of alternative investments, including private-market opportunities. 3. Liquidity and Investment Horizon Liquidity is an important consideration when comparing these investment structures. SIFs may offer open-ended, close-ended or interval-based investment strategies. Redemption frequency and other restrictions depend on the specific strategy’s documents. Many Category I and Category II AIF schemes are close-ended and may require investors to commit capital for several years. Category III AIFs may be open-ended or close-ended, depending on their structure. Investors should review redemption terms, lock-in periods, exit provisions and the possibility of delays in accessing their money. An investment with a high return target may still be unsuitable if the investor needs regular access to the invested capital. 4. Risk and Return Potential Both investment structures involve market and investment risks, but the nature of those risks can differ. SIFs may carry additional risks associated with derivatives, short exposure, concentrated positions and specialised trading strategies. AIFs may involve risks linked to illiquid assets, private-market valuations, leverage, concentrated investments and long investment commitments. The risk profile can vary substantially between venture capital funds, private debt funds and Category III trading strategies. Neither SIFs nor

Crude Oil at $100: Does It Really Mean a Stock Market Crash?

Crude oil at $100 per barrel often raises concerns among Indian investors about inflation, corporate earnings and a potential stock market correction. India depends heavily on imported crude oil, making sustained increases in global oil prices an important economic risk. Higher oil prices can increase India’s import bill, put pressure on the rupee, raise transportation costs and reduce corporate profit margins. However, historical market performance suggests that expensive crude does not automatically trigger a stock market crash. India has experienced periods when oil prices remained above $100 per barrel while equities subsequently delivered positive returns. The outcome depends on several factors, including the duration of high prices, inflation, interest rates, economic growth, market liquidity and corporate earnings. For investors in 2026, the important question is not simply whether oil has crossed $100. It is how long prices remain elevated and how significantly they affect India’s economy and businesses. Disclaimer: This article is for educational and informational purposes only and should not be considered investment advice. Why Does $100 Crude Matter for India? Crude oil affects much more than the energy sector. Because India imports a substantial portion of its crude requirements, a sustained increase in global prices can influence several parts of the economy. 1. Higher Import Bill Rising oil prices increase the cost of India’s energy imports. If import expenditure rises faster than export earnings, pressure on the trade balance and current account can increase. 2. Pressure on the Rupee India generally pays for crude imports in US dollars. Higher oil prices can increase demand for dollars, potentially putting pressure on the rupee. A weaker rupee can make imported energy and other commodities more expensive in domestic currency terms. 3. Inflationary Pressure Higher fuel, freight and transportation costs can gradually affect the prices of goods and services. Businesses may pass some of these costs on to consumers, depending on market conditions. 4. Interest Rates If higher oil prices contribute to persistent inflation, the Reserve Bank of India (RBI) may have less room to ease monetary policy. Higher interest rates for longer can affect borrowing costs, consumption, investment and equity valuations. 5. Corporate Earnings Businesses with significant exposure to energy, transportation, imported inputs or petroleum-based raw materials may face pressure on their margins. The overall impact depends on how much of the additional cost a company can pass on to customers. The key distinction is between a temporary increase in crude prices and a prolonged oil shock. Their economic consequences can be very different. What History Tells Us About High Crude Prices Previous oil shocks provide useful context for understanding how Indian equities may respond to elevated energy prices. However, historical comparisons must account for the broader economic and financial conditions prevailing during each period. 2008: Oil Above $100 During the Global Financial Crisis In 2008, Brent crude rose sharply during the first half of the year, crossing $120 per barrel and reaching approximately $145 during the summer. At the same time, Indian equities experienced a severe decline as the global financial crisis intensified. The Sensex fell by more than 50% during the calendar year. However, crude oil was not the sole cause of the market collapse. The global financial crisis, deteriorating credit conditions, investor risk aversion and weakening economic expectations were major factors. Expensive oil added to India’s inflationary and external-balance pressures. The lesson from 2008 is important: high crude can amplify an existing economic or financial crisis, but it does not necessarily cause a stock market crash on its own. Investors should distinguish between a commodity-price shock and the broader economic conditions surrounding it. 2011–2014: High Oil Prices Did Not Prevent Market Gains The period from 2011 to 2014 provides another useful historical example. Brent crude remained above $100 per barrel for much of this period, while India faced slowing growth, persistent inflation and pressure on the rupee. The Sensex declined significantly in 2011. However, the subsequent years produced a different outcome. Year Sensex Performance, Approximately 2011 -25% 2012 +25.7% 2013 +9% 2014 +30% Historical figures are rounded and may vary slightly by data source and measurement methodology. Despite expensive oil, Indian equities recovered and delivered strong gains in subsequent years. Why did the outcome change? Market expectations, valuations, domestic economic conditions and policy developments evolved. Investors began assessing the outlook beyond the prevailing crude price. This period demonstrates that the stock market responds to the economic consequences of high oil prices, not just the headline price itself. 2022: Another Oil Shock, Another Lesson Russia’s invasion of Ukraine in 2022 triggered a major energy-market shock. Brent crude rose above $100 per barrel, increasing concerns about inflation, global growth and energy security. Despite these pressures, the Sensex ended calendar 2022 with a positive return of approximately 4.4%, although markets experienced volatility during the year. Domestic economic growth, institutional flows, corporate earnings and investor sentiment influenced the overall outcome. This does not mean expensive crude was harmless. Rather, it demonstrates that oil prices are only one of several factors affecting equities. 2026: Crude Oil Crosses $100 Again The renewed rise in oil prices during 2026 makes these historical lessons relevant for Indian investors. Because India relies heavily on imported crude, sustained price increases can create pressure across the economy. The transmission mechanism can be summarised as: Crude oil → Import bill → Rupee → Inflation → Interest rates → Corporate earnings → Stock valuations Each stage can influence the next, although the effects depend on policy responses, global conditions and domestic demand. The most important question is therefore: Will elevated crude prices remain a temporary shock, or will they become a prolonged economic headwind? That distinction matters more than the $100 threshold alone. What Makes the 2026 Oil Environment Important? 1. Duration Matters More Than the Headline Price A short-lived increase in crude prices may have a limited economic impact. If prices remain elevated for several months, the effects can become more significant. A prolonged oil shock can affect: Investors should therefore track the persistence of higher prices rather

Mutual Fund Investing: Patience vs Performance – What Really Builds Wealth?

The secret to mutual fund investing is not just how much you earn, but how long you stay invested and how wisely you manage your investments. Introduction: Wealth Is a Journey, Not a Race In a world where everyone wants quick results, investors often judge success by short-term returns. When a mutual fund performs well, it attracts attention. When markets fall, fear and uncertainty can influence investment decisions. Many investors switch funds, stop their Systematic Investment Plans (SIPs), or search for the latest top-performing scheme. But is chasing the highest return really the best way to build wealth? Performance may attract investors, but patience, discipline and informed decisions can help them stay focused on their financial goals. Successful investing is not about winning every day. It is about choosing suitable investments, understanding the associated risks and following a strategy aligned with your financial objectives. 1. Performance Looks Impressive, but Consistency Matters Imagine two investors. The first constantly searches for the best-performing mutual fund and changes investments whenever another scheme delivers higher returns. The second chooses funds based on financial goals, risk tolerance and investment horizon, reviewing them periodically. The first investor may occasionally benefit from switching, but frequent changes can lead to poor timing, additional costs and emotional decisions. The second follows a more structured approach rather than reacting to every market movement. Past performance can provide useful insights, but it does not guarantee future returns. A fund that performs exceptionally well in one year may not remain a top performer in the next. Before choosing a mutual fund, consider: The key lesson: Do not judge an investment solely by its latest returns. Evaluate performance alongside risk, costs and long-term suitability. 2. Patience: The Power Behind Long-Term Wealth Patience is an important part of investing, but it does not mean ignoring your investments or holding every fund indefinitely. It means understanding that market fluctuations are normal and that financial goals often require time. Equity mutual funds can experience significant short-term volatility. Investors with an appropriate long-term horizon may have more time to navigate market fluctuations, although losses remain possible. Consider two different financial goals: Their investment choices should reflect these different needs and risk capacities. Patience gives a suitable investment strategy time to work. However, it cannot eliminate market risk or guarantee positive returns. 3. The Power of SIPs and Compounding A Systematic Investment Plan (SIP) allows investors to contribute a fixed amount regularly to a mutual fund. It can encourage financial discipline and reduce the pressure of deciding when to invest a large sum. Over time, regular contributions and compounding may contribute meaningfully to wealth creation. An Illustrative SIP Investment Example Suppose an investor invests ₹1,00,000 every month for 20 years. Investment Parameter Illustration Monthly investment ₹1,00,000 Investment period 20 years Total amount invested ₹2.40 crore Assumed annualized return 10% Potential investment value Approximately ₹7.59 crore Illustration only: The estimate assumes monthly investments and a constant 10% annualized return, compounded monthly. Actual mutual fund returns fluctuate, and the final value may be substantially higher or lower. This is not a forecast or a guaranteed return. How Does Compounding Work? Compounding occurs when investment earnings generate further earnings over time. As an investment grows, returns earned in earlier periods can contribute to future growth. Regular contributions can add to this effect by increasing the amount invested over time. However, compounding does not mean returns will be positive every year. Market-linked investments can decline in value, and actual results depend on market performance, costs and the timing of contributions. The takeaway: Regular investing, time and realistic return expectations can work together to support long-term financial planning. 4. Why Investors Often Make Emotional Mistakes Investment decisions are not always driven by financial analysis. Fear and greed can influence even experienced investors. When markets rise, investors may rush into funds after strong returns. When markets fall, they may panic, redeem their investments or discontinue SIPs because they fear further losses. Repeatedly switching funds in search of quick gains can also distract investors from their original financial goals. A disciplined investor should ask three questions before making a change: The objective is not to ignore market risks. It is to respond thoughtfully rather than impulsively. 5. Patience vs Performance: Why Investors Need Both Patience alone is not enough. Investors should not hold an unsuitable or consistently underperforming fund indefinitely simply because they believe in staying invested. Performance analysis remains essential when conducted in the right context. Investors can assess whether a fund: Performance should be reviewed over an appropriate period rather than judged solely on a few weeks or months. If a fund experiences persistent underperformance, significant strategy changes or an unacceptable level of risk, a detailed review may be appropriate. The real difference is between disciplined patience and blind loyalty. Disciplined patience means allowing a suitable investment sufficient time to perform while remaining alert to meaningful changes in its fundamentals, strategy and risk profile. 6. Six Habits That Can Support Long-Term Wealth Creation Building wealth through mutual funds requires more than selecting a scheme with attractive past returns. A consistent investment process can help investors make better-informed decisions. 1. Set Clear Financial Goals Identify what you are investing for, whether it is retirement, education, a home or another long-term objective. Your goal helps determine the investment horizon and the level of risk you can reasonably accept. 2. Choose Funds According to Your Risk Profile Different mutual fund categories have different risk characteristics. Select investments based on your financial situation, time horizon and ability to withstand losses. 3. Invest Regularly SIPs can help establish a consistent investment habit. However, regular investing does not eliminate market risk or guarantee profits. 4. Diversify Appropriately Avoid excessive concentration in a single company, sector or investment category. Diversification can help manage certain risks, although it cannot prevent all losses. 5. Review Investments Periodically Evaluate performance, risk, expenses and continued suitability. Avoid unnecessary changes driven by short-term market movements. 6. Stay Focused on Your Long-Term Plan Short-term fluctuations

October 2026 Stock Market Outlook: 10 Stocks, Sectors and Trends Investors Should Watch

The October 2026 stock market outlook is shaped by several important factors, including Q2 FY27 earnings, crude oil prices, RBI policy, foreign institutional flows, domestic liquidity, artificial intelligence and major corporate developments such as the expected Jio Platforms IPO. Rather than trying to predict whether the overall market will rise or fall, investors may benefit from focusing on a more fundamental question: Which businesses have strong earnings visibility, healthy balance sheets, sustainable growth and reasonable valuations? October could remain a stock-pickers’ market, where company-specific earnings and sector trends may matter more than short-term movements in the broader indices. Disclaimer: This article is for educational and informational purposes only. It should not be considered investment advice or a recommendation to buy or sell any security. 1. Indian Equity Market Outlook: Volatility Could Continue Indian equities are entering October amid several competing market forces. Global bond yields, crude oil prices, foreign institutional activity, geopolitical developments and monetary-policy expectations could continue to influence sentiment. On October 5, the Nifty 50 gained around 0.60% to close at 22,555.75, while the Sensex rose around 0.66% to 72,382.47. However, a few positive trading sessions do not necessarily indicate the beginning of a sustained market rally. For investors, the more important consideration is whether individual companies can deliver earnings growth despite changing macroeconomic conditions. Why Individual Stocks Can Outperform Company-specific performance can be influenced by: This means market direction and individual stock performance do not always move together. 2. Q2 FY27 Earnings Could Be the Biggest Catalyst The September-quarter earnings season is likely to be one of the most important drivers of Indian equities during October. Investors should look beyond headline profit numbers and examine the quality and sustainability of earnings. Key Earnings Metrics to Track Revenue growth: Is the company growing faster than its industry? EBITDA margin: Are input costs affecting profitability? Profit growth: Is earnings growth sustainable? EPS: Are earnings estimates being upgraded or downgraded? Debt: Is leverage increasing or declining? Operating cash flow: Is reported profit translating into actual cash generation? Order book: Does the company have sufficient future revenue visibility? Management guidance: What does management expect for the second half of FY27? Valuation: Does the current price reasonably reflect the company’s growth prospects? Markets often react not only to actual results but also to the difference between market expectations and reported performance. For example, a company reporting 15% profit growth could see its stock decline if investors were expecting 25% growth. Conversely, moderate growth could support a positive market reaction if the results significantly exceed expectations. Therefore, October should be viewed as an earnings-focused month, rather than simply an index-focused month. 3. Banking and Financials: Credit Growth in Focus Banks remain an important indicator of economic activity and credit demand. Recent Q2 business updates from private-sector banks have highlighted continued balance-sheet expansion. Axis Bank reported gross advances of about ₹13.85 lakh crore, up 22.7% year-on-year, while deposits increased 20.7% to approximately ₹14.52 lakh crore. Kotak Mahindra Bank reported net advances rising 24.7% year-on-year to approximately ₹5.77 lakh crore, while deposits increased 23.2% to around ₹6.51 lakh crore. For investors, strong loan growth needs to be assessed alongside asset quality and profitability. Banking Metrics to Watch Stocks to Watch Axis Bank and Kotak Mahindra Bank The key consideration is not simply how quickly loans are growing, but whether that growth is supported by healthy asset quality, adequate capital and sustainable profitability. 4. Retail and Consumption: Trent in Focus India’s consumption story remains an important long-term investment theme, particularly across organised retail and branded consumer businesses. Trent reported standalone Q2 revenue of ₹5,788 crore, representing approximately 23% year-on-year growth. The company also added 10 Westside stores and 17 Zudio stores during the quarter. The expansion highlights the continued development of India’s organised retail market. Consumption Trends to Monitor However, strong revenue growth alone does not determine whether a stock is attractively valued. The important question is whether future earnings growth can justify the current valuation. 5. FMCG: Growth Versus Input Costs FMCG companies could remain in focus as investors assess volume growth, pricing power and margins. Godrej Consumer Products has indicated expectations of strong Q2 performance, including high-teens consolidated revenue growth along with healthy volume and EBITDA growth despite commodity-cost pressures. FMCG companies can benefit from established brands, extensive distribution networks and relatively defensive demand characteristics. At the same time, rising commodity prices can put pressure on profitability. Investors should therefore monitor the relationship between: Raw-material inflation → Gross margin → EBITDA margin → Profit growth Revenue growth becomes more meaningful when it is supported by sustainable margins and improving cash generation. 6. IT Stocks: AI Creates Both Opportunity and Disruption Artificial intelligence is emerging as one of the most important structural themes for India’s technology sector. TCS, Infosys and HCLTech are entering the earnings season amid questions around discretionary technology spending, AI-driven productivity and potential pricing pressure. At the same time, increasing adoption of AI could create new opportunities across: The long-term opportunity for Indian IT companies may depend on how effectively they transition from traditional services toward higher-value technology solutions. The Key Question for IT Investors Is AI disrupting the traditional IT services model, or could it create the next major technology growth cycle? Q2 earnings and management commentary could provide important signals regarding technology spending, deal pipelines, margins and demand. 7. Reliance Industries and the Jio Platforms IPO The proposed Jio Platforms IPO could become one of the major corporate events for Indian investors. Reports have indicated a potential issue size of approximately $3.8 billion and an expected October 21 opening. However, investors should rely on official company, exchange and regulatory disclosures for final dates, pricing and issue terms. The IPO could also influence how investors value Reliance Industries’ digital businesses. Jio Platforms operates across areas including: What Investors Should Monitor The broader question is whether India’s rapidly expanding digital economy can successfully move from user acquisition to sustainable monetisation. 8. Crude Oil: A Market-Wide Macro Variable Crude oil remains one

Money Management: The Most Important Class You Never Had

Money Management is one of the most important life skills, yet schools and colleges rarely teach it in a structured way. We spend years learning mathematics, science, history and other subjects. However, we often receive little practical guidance on how to earn, budget, save, invest and plan for the future. Earning money is important. However, knowing how to manage what you earn can make an equally important difference to your financial life. Good financial management does not necessarily require a high income. Instead, it requires informed decisions about the money you already have and a system that supports your financial goals. What Does Money Management Really Mean? Managing money involves much more than putting some money aside every month. A practical financial framework can follow these five steps: Earn → Manage → Save → Invest → Grow First, understand your income and expenses. Next, create a realistic budget and build an emergency fund. After that, manage debt, define your financial goals and invest according to your circumstances. For many investors, mutual funds can form part of a long-term investment strategy. However, the suitability of an investment depends on factors such as financial goals, time horizon and risk profile. The 50-30-20 Rule: A Simple Starting Point One commonly used budgeting framework is the 50-30-20 rule. The approach divides income into three broad categories: Category Suggested Allocation Examples Needs 50% Rent, groceries, utilities, transportation and essential expenses Wants 30% Entertainment, shopping, dining out and lifestyle expenses Savings & Investments 20% Emergency savings, SIPs and other investments These percentages do not need to remain exactly the same for everyone. For example, someone with high housing costs may need a different allocation. Meanwhile, another person may have enough flexibility to save and invest a larger portion of their income. Therefore, the main purpose of this framework is not to follow fixed numbers blindly. Instead, it helps create awareness and encourages intentional saving and investing habits. Saving Is Important, but Investing Has a Different Purpose Saving and investing serve different financial purposes. Savings can provide liquidity for emergencies and short-term requirements. Investing, meanwhile, generally focuses on longer-term financial objectives and involves different levels of risk. Consider two approaches: Person A:Earn → Spend → Save whatever remains Person B:Earn → Save/Invest first → Spend what remains The second approach follows the principle of “paying yourself first.” Instead of waiting to see what remains at the end of the month, you give saving and investing a defined place in your monthly budget. A Systematic Investment Plan (SIP) can support this habit by allowing investors to invest a predetermined amount at regular intervals in a mutual fund scheme. However, a SIP does not guarantee profits or protect investors from market losses. The Power of Starting Early One of the most important concepts in long-term investing is compounding. Compounding occurs when returns generated by an investment contribute to potential future growth over time. For example, suppose an investor contributes ₹5,000 every month. Over one year: ₹5,000 × 12 = ₹60,000 The monthly contribution may appear small. However, regular investments over a long period can potentially build a larger investment corpus, depending on the returns generated by the underlying investments. Therefore, time can play an important role in long-term wealth creation. Start with an amount you can afford. Stay consistent. Most importantly, give your investments sufficient time to work. Returns from mutual funds are market-linked, so actual results can vary. Mutual Funds: A Structured Way to Invest For many individuals, researching individual stocks, bonds and different asset classes can feel challenging. Mutual funds pool money from multiple investors and invest that money according to the investment objective of each scheme. Depending on the scheme, a mutual fund may invest in: As a result, investors can choose from different investment approaches. However, the appropriate option depends on factors such as financial goals, investment horizon, risk tolerance and overall financial circumstances. Don’t Invest Simply Because Everyone Else Is Investing One of the most useful financial habits is to give every investment a purpose. Instead of starting with: “Which investment is giving the highest return?” Start with: “What am I investing for?” For example: Financial Goal Possible Investment Approach Emergency needs Liquid or lower-risk avenues appropriate for short-term requirements Short-term goals Options aligned with the shorter investment horizon Children’s education Goal-based long-term investment strategy Retirement Long-term diversified investment strategy Wealth creation Long-term equity-oriented investments, depending on risk profile There is no single investment product that suits every financial goal. For instance, an investment intended for a requirement five years from now may need a different approach from money invested for retirement several decades away. Therefore, investors should consider the purpose and time horizon before selecting an investment. SIP Is a Habit, Not a Shortcut Many investors misunderstand SIPs as a method for generating guaranteed returns. That is not how a SIP works. Instead, a SIP provides a method of investing regularly. By investing a predetermined amount at regular intervals, investors can develop a systematic investing habit. Regular contributions also mean that purchases occur across different market conditions instead of relying entirely on attempts to identify the perfect entry point. For example: ₹5,000 per month × 12 months = ₹60,000 invested in one year Over longer periods, regular contributions can build a larger invested amount. However, the final value depends on the performance of the underlying investments and other factors. Therefore, investors should view SIPs as a discipline and investment mechanism, rather than a promise of returns. Understand Risk Before Chasing Returns Investment decisions should not depend solely on historical returns. Before selecting a mutual fund or another investment, consider these questions: A fund that performed strongly in the past may not deliver the same results in the future. Therefore: Past performance is not a guarantee of future returns. Understanding risk can help investors make more informed investment decisions. The Biggest Mistake: Investing Without a Financial Plan Some investors accumulate multiple investments without creating a clear strategy. One SIP may start because a

Investment Losses: Understanding Recovery Math and Capital Preservation

Investment losses are not symmetrical with gains. When a portfolio declines, the percentage return required to recover the lost value is usually greater than the percentage decline itself. Understanding this recovery math is essential for investors who want to manage risk and build wealth over the long term. For example, a 20% decline does not require a subsequent 20% gain to return to the original value. After falling 20%, the portfolio needs to rise by 25% from its reduced value. The larger the decline, the more difficult the recovery becomes. This is one reason why capital preservation, diversification, appropriate position sizing and disciplined investing can play an important role in long-term wealth creation. Understanding the Mathematics of Investment Losses The relationship between a portfolio decline and the gain required to recover can be expressed using a simple formula: Required Recovery Gain = Loss ÷ (1 − Loss) Here, the loss is expressed as a decimal. For example, if a portfolio declines by 40%: 40% ÷ (1 − 40%) = 40% ÷ 60% = 66.67% Therefore, a 40% decline requires a gain of approximately 66.67% simply to return to the original portfolio value. The recovery requirement becomes increasingly significant as the size of the decline increases. Loss and Recovery Requirements Portfolio Loss Gain Required to Recover -10% +11.11% -20% +25.00% -30% +42.86% -40% +66.67% -50% +100.00% -60% +150.00% -70% +233.33% -80% +400.00% -90% +900.00% The table highlights an important principle: the deeper the decline, the disproportionately larger the subsequent return required for recovery. A Simple ₹10 Lakh Example Suppose an investor has a portfolio worth ₹10 lakh. If the portfolio falls by 20%, its value becomes: ₹10 lakh × 80% = ₹8 lakh The investor has lost ₹2 lakh. To return from ₹8 lakh to ₹10 lakh, the portfolio needs to gain ₹2 lakh. However, ₹2 lakh is 25% of ₹8 lakh, not 20%. So: ₹2 lakh ÷ ₹8 lakh × 100 = 25% This demonstrates why percentage declines and percentage gains cannot simply be treated as equal and opposite movements. What Happens After a 50% Decline? A 50% decline is particularly important because the remaining capital must double to return to the original value. Starting value: ₹10 lakh After a 50% decline: ₹5 lakh Required recovery: ₹5 lakh Therefore: ₹5 lakh ÷ ₹5 lakh × 100 = 100% The portfolio must generate a 100% return from ₹5 lakh to reach ₹10 lakh again. What Happens After a 90% Decline? The mathematics become even more significant after a very large drawdown. Starting value: ₹10 lakh After a 90% decline: ₹1 lakh To return to ₹10 lakh, the investor needs another ₹9 lakh. Therefore: ₹9 lakh ÷ ₹1 lakh × 100 = 900% A 90% decline therefore requires a 900% gain to recover the original capital. Why Does Recovery Become More Difficult? The reason is simple: the percentage gain is calculated on the reduced capital base. Consider a portfolio that falls from ₹10 lakh to ₹6 lakh. The investor has lost ₹4 lakh. To recover, the portfolio needs to gain ₹4 lakh. But ₹4 lakh represents: ₹4 lakh ÷ ₹6 lakh × 100 = 66.67% So the portfolio requires a 66.67% return, even though the original decline was only 40%. This mathematical relationship is important because investors often focus on the percentage decline without considering the return required afterward. What Happens When an Investor Adds More Capital? Additional investment after a decline changes the mathematics because the investor is increasing the amount of capital exposed to the portfolio. Suppose an investor initially invests ₹10 lakh and the portfolio falls by 50%. After the decline: At this point, the investor has ₹10 lakh in the portfolio but has invested ₹15 lakh in total. To recover the total amount invested, the portfolio needs to increase from ₹10 lakh to ₹15 lakh. The required gain is: ₹5 lakh ÷ ₹10 lakh × 100 = 50% Therefore, the portfolio needs a 50% gain from its post-additional-investment value to reach ₹15 lakh. However, this does not mean the original 50% decline has somehow been erased. The investor has committed additional capital, increasing the total amount at risk. Without Additional Capital vs. With Additional Capital Situation Portfolio Value Total Capital Invested Gain Required to Recover Total Capital 50% decline, no additional investment ₹5 lakh ₹10 lakh 100% 50% decline + ₹5 lakh additional investment ₹10 lakh ₹15 lakh 50% The key difference is that the investor has changed the capital base by contributing additional funds. Adding money after a decline may reduce the percentage return required from the existing portfolio value to reach the total amount invested, but it also increases the investor’s overall financial exposure. Equal Additional Investment After a Loss An interesting mathematical relationship appears when an investor adds an amount equal to the money lost. Suppose the original investment is ₹10 lakh. If the portfolio loses 20%, the investor loses ₹2 lakh. If the investor then adds another ₹2 lakh, the portfolio value returns to ₹10 lakh, while total capital invested becomes ₹12 lakh. The portfolio now needs to grow by ₹2 lakh to reach ₹12 lakh. That represents: ₹2 lakh ÷ ₹10 lakh × 100 = 20% The same relationship applies across different loss levels. Portfolio Loss Amount Lost Amount Remaining Additional Investment Portfolio Value After Adding Total Capital Invested Gain Required Required Gain % -10% ₹1L ₹9L ₹1L ₹10L ₹11L ₹1L 10% -20% ₹2L ₹8L ₹2L ₹10L ₹12L ₹2L 20% -30% ₹3L ₹7L ₹3L ₹10L ₹13L ₹3L 30% -40% ₹4L ₹6L ₹4L ₹10L ₹14L ₹4L 40% -50% ₹5L ₹5L ₹5L ₹10L ₹15L ₹5L 50% -60% ₹6L ₹4L ₹6L ₹10L ₹16L ₹6L 60% -70% ₹7L ₹3L ₹7L ₹10L ₹17L ₹7L 70% -80% ₹8L ₹2L ₹8L ₹10L ₹18L ₹8L 80% -90% ₹9L ₹1L ₹9L ₹10L ₹19L ₹9L 90% Why Does the Required Gain Equal the Loss Percentage? The reason is that the investor adds exactly the amount that was lost. For example, after a 40% decline: The portfolio needs another ₹4 lakh to reach

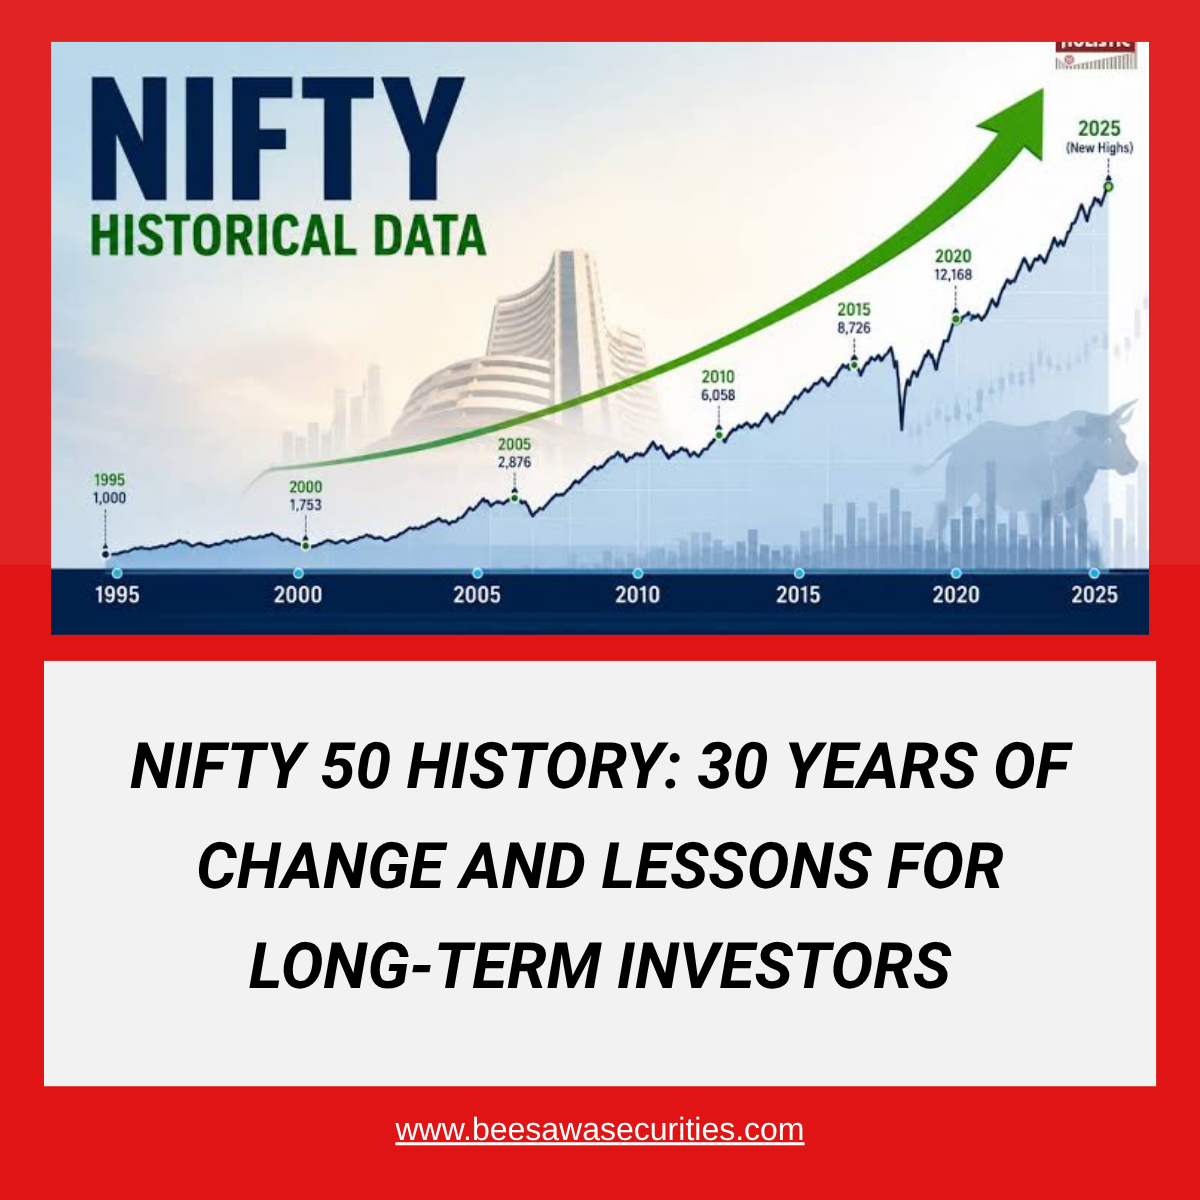
Nifty 50 History: 30 Years of Change and Lessons for Long-Term Investors

Nifty 50 History provides a fascinating view of how India’s corporate landscape has changed over the past three decades. Since the index’s base date in 1995, India has experienced economic reforms, technological disruption, new industries, changing consumer behaviour, financialisation and several major market cycles. Yet, among the companies that formed part of the Nifty 50 at inception, only 11 remained current constituents as of February 27, 2026, according to the source material based on NSE Indices’ 2026 research. This evolution offers an important perspective for long-term investors: today’s market leaders may not necessarily remain tomorrow’s leaders. The 11 Original Companies That Remained The companies identified as current constituents from the original Nifty 50 group as of February 27, 2026 are: No. Company 1 Reliance Industries 2 HDFC Bank 3 ICICI Bank 4 State Bank of India 5 Larsen & Toubro 6 ITC 7 Hindustan Unilever 8 Tata Steel 9 Hindalco Industries 10 Bajaj Auto 11 Tata Motors Passenger Vehicles The source also notes an important historical detail concerning HDFC Ltd. HDFC Ltd. was part of the index from inception and later merged with HDFC Bank in 2023. This helps explain the difference between earlier references to 12 companies from inception and the 11 current constituents identified in the 2026 research. The Nifty 50 Is an Evolving Index The Nifty 50 was created to represent an evolving cross-section of India’s large and liquid companies. Its base date is November 3, 1995, with a base value of 1,000. Since then, India’s economy has undergone significant structural changes, including: The index has evolved alongside these developments. Companies can enter or leave the index as their market capitalisation, liquidity and eligibility change under the applicable methodology. Therefore, the Nifty 50 should be viewed as a changing representation of corporate India rather than a permanent list of companies. Why the Long-Term Constituents Are Significant The companies that have remained connected with the index over such an extended period represent businesses that have operated through multiple economic and industry cycles. Their individual histories also demonstrate how companies can change as markets evolve. 1. Reliance Industries Reliance Industries has evolved from a business strongly associated with energy and petrochemicals into a diversified group with activities spanning energy, refining, petrochemicals, retail, telecommunications, digital services and new-energy initiatives. Its history illustrates how diversification can accompany changes in economic opportunities. 2. HDFC Bank HDFC Bank represents the development of India’s private banking sector, including the expansion of retail banking, consumer credit, digital banking and technology-driven financial services. The merger between HDFC Ltd. and HDFC Bank also demonstrates how corporate structures can change while business franchises continue through restructuring. 3. ICICI Bank ICICI Bank has participated in India’s transition toward private banking, retail financial services and digital banking. Its history also reflects the broader development of financialisation within the Indian economy. 4. State Bank of India State Bank of India represents the scale and importance of India’s banking infrastructure. Its long-standing presence highlights how established financial institutions can remain relevant while technology and customer behaviour continue to change. 5. Larsen & Toubro Larsen & Toubro is closely connected with India’s infrastructure and capital-investment cycle. Its businesses span engineering, construction, infrastructure, technology, defence, energy and other industrial activities. 6. ITC ITC has historically been strongly associated with cigarettes while also developing businesses across FMCG, hotels, paperboards, packaging and agri-business. Its evolution demonstrates the role diversification can play in developing multiple business segments. 7. Hindustan Unilever Hindustan Unilever represents India’s long-term consumption story. Its businesses across household products, personal care, food and other everyday categories are connected with changing income levels, urbanisation and consumer preferences. 8. Tata Steel Steel is a cyclical industry, with profitability influenced by global demand, commodity prices, energy costs, interest rates and industry supply. Tata Steel’s long association with the index demonstrates how an industrial business can remain significant across multiple economic cycles. 9. Hindalco Industries Hindalco represents India’s metals and manufacturing ecosystem, with exposure to aluminium and copper as well as significant international operations. Its history highlights the continued role of industrial and commodity businesses alongside technology and consumer sectors. 10. Bajaj Auto India’s automobile industry has changed substantially since the 1990s. Bajaj Auto has participated in this transformation through motorcycles, exports, premium products and developments in electric mobility. The wider mobility sector continues to evolve with technology, regulation and changing consumer preferences. 11. Tata Motors Passenger Vehicles The current corporate name reflects Tata Motors’ restructuring and the passenger-vehicle business lineage. The automobile sector has moved from conventional internal-combustion vehicles toward SUVs, connected vehicles and electric mobility. This history illustrates how established businesses can operate through major technological and consumer shifts. The Biggest Lesson: Index Membership Changes One of the clearest lessons from the index’s evolution is that today’s index is not necessarily tomorrow’s index. At inception, there were 50 constituents. Nearly three decades later, only 11 of those original companies remained current constituents as of February 27, 2026. Based on those figures: These changes should be understood in the context of how an index works. Companies grow or decline. Industries expand or contract. Business models become outdated. New technologies create new opportunities. As the market changes, index composition changes as well. What Does This Mean for Long-Term Investors? A common idea in long-term investing is to identify a good company and hold it for many years. However, a long investment horizon does not mean ignoring changes in a company’s fundamentals. A more useful question can be: Is the original investment thesis still intact? A business may have strong fundamentals today but face different competitive conditions a decade or two later. Investors can therefore monitor factors such as: Long-term investing does not necessarily mean ignoring change. It can instead involve remaining invested in businesses whose fundamentals continue to support the original investment thesis. The Structural Advantage of Index Investing The changing composition of the Nifty 50 also highlights a feature of index investing. An investor selecting individual stocks needs to continually assess whether businesses can remain successful